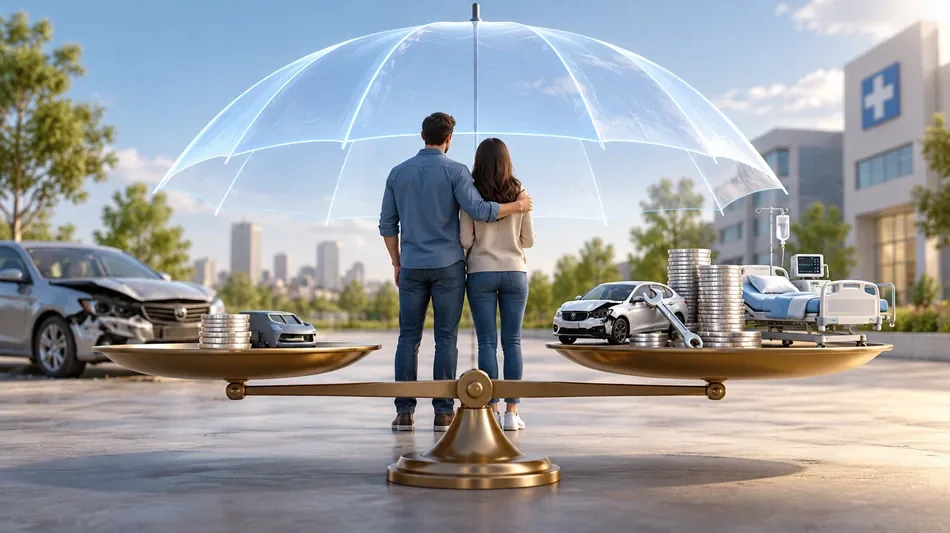
Insurance deductibles and no-claim bonuses require a careful claims decision
 Argentine police arrest stepfather after pregnant 10-year-old reaches hospital
 Mother dies after rescuing sons from riptide in the Bahamas
 Body recovered after ferry passenger reported overboard
 UK households advised to prepare for three days without essential services
 UP schools close for Valmiki Jayanti as coastal states monitor cyclone risk
 NPS Vatsalya offers three choices when a child turns 18
 From Carnegie to Claude: AI wealth could reshape philanthropy
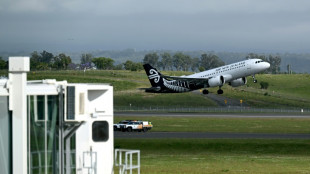 First international flight takes off from new Sydney airport
 Readers debate YES Bank bonds, climate commitments and candidate disclosure
 Nifty heads toward weakest Samvat of Modi era after 13% fall
 Bleems adds UFFF toys and collectibles through Kuwait partnership
 Kuwait regulators broaden beneficial-owner data cooperation
 IMF sees regional economy shrinking 1.3% in 2026 amid Iran war
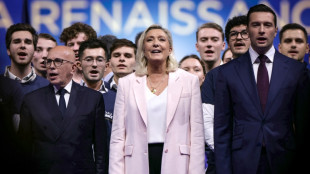 France's Le Pen launches presidential bid vowing to restore 'rule of law'
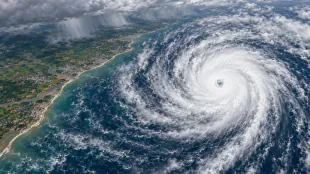 Bay cyclone forecast to strike Andhra-Yanam coast at very severe strength
 UDST opens Fall 2027 admissions to students in Qatar and abroad
 Kuwait legal department reviews new commercial concealment law
 IRDAI gives stakeholders until October 31 to comment on distribution reforms
 Credit-card shortcuts can turn impulse spending into lasting debt
 J&K Bank raises accident cover for government employees to ₹1 crore
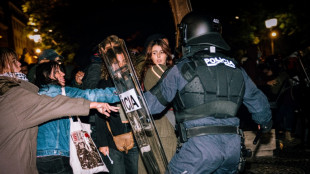
 Far-right leader Le Pen kicks off tilt at French presidency amid nationwide protests
Policyholders should weigh the deductible and possible loss of a no-claim bonus before filing a small motor or health insurance claim.
An insurance excess, also called a deductible, is the first part of an admissible claim that the policyholder must pay. Although this amount may appear small compared with the value insured, it affects both the insurer’s payment and the policyholder’s decision to claim.
A policy with a ₹1,000 excess would pay ₹1,500 on an admissible ₹2,500 loss. A customer may decide the smaller recovery does not justify making a claim. This reduces the number of low-value claims and the administrative time and expense required to process them.
Motor and health policyholders also need to consider the no-claim bonus, or NCB. Depending on the policy, a claim-free year may earn a renewal-premium discount or an increase in the sum insured. Making a claim can reduce or eliminate an accumulated benefit.
For example, consider a car policy with an annual own-damage premium of ₹10,000 before the NCB and an accumulated 50% bonus. If the base premium is unchanged, the policyholder would pay ₹5,000 on renewal. An admissible own-damage claim of only ₹2,000 could remove the bonus and restore the premium to ₹10,000.
In that example, the lost ₹5,000 discount exceeds the value of the claim. A policyholder deciding whether to report a small loss should therefore compare the expected payout with the value of the no-claim benefit that could be forfeited.
The calculation varies by contract. Health-insurance NCB rules do not necessarily work in the same way as motor cover, and some motor policies include protection for the no-claim bonus. Customers should check the wording of their own policy before deciding.
The excess also reinforces the insured person’s obligation to take reasonable precautions. Insurance operates on the expectation that a policyholder will behave as a prudent uninsured person would, working to prevent a loss and limit its consequences.
Because the customer retains part of the financial risk, the deductible provides an incentive to protect the insured property and avoid preventable losses. It is comparable to a borrower contributing a margin to a home purchase while the lender finances the larger share.
Insurance is therefore not designed to remove every financial consequence of every event. It covers specified risks while leaving the policyholder responsible for the agreed portion. An excess is part of that design, rather than necessarily a gap in protection.
A.Leibowitz--CPN