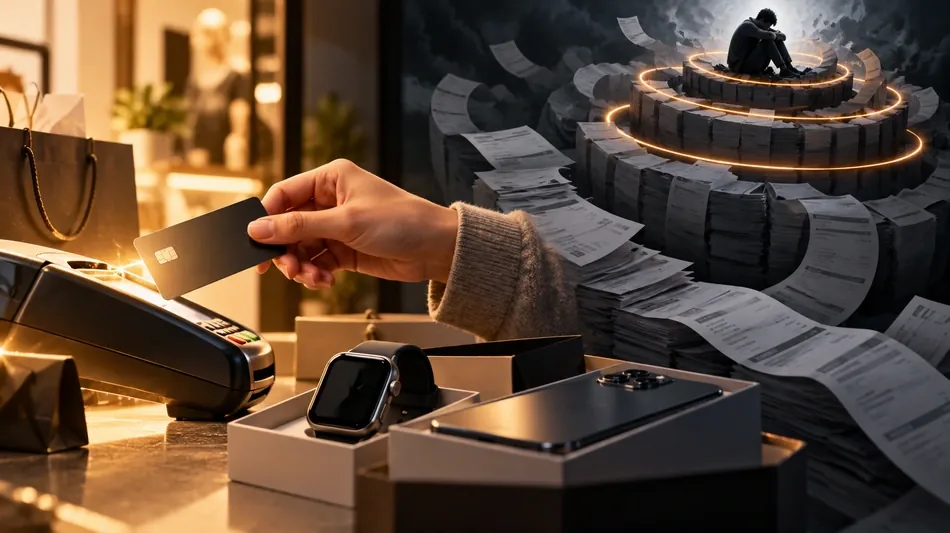
Credit-card shortcuts can turn impulse spending into lasting debt
 Argentine police arrest stepfather after pregnant 10-year-old reaches hospital
 Mother dies after rescuing sons from riptide in the Bahamas
 Body recovered after ferry passenger reported overboard
 UK households advised to prepare for three days without essential services
 UP schools close for Valmiki Jayanti as coastal states monitor cyclone risk
 NPS Vatsalya offers three choices when a child turns 18
 From Carnegie to Claude: AI wealth could reshape philanthropy
 First international flight takes off from new Sydney airport
 Readers debate YES Bank bonds, climate commitments and candidate disclosure
 Nifty heads toward weakest Samvat of Modi era after 13% fall
 Bleems adds UFFF toys and collectibles through Kuwait partnership
 Kuwait regulators broaden beneficial-owner data cooperation
 IMF sees regional economy shrinking 1.3% in 2026 amid Iran war
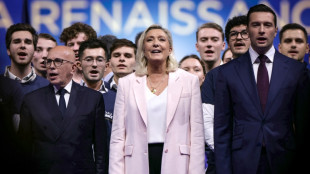 France's Le Pen launches presidential bid vowing to restore 'rule of law'
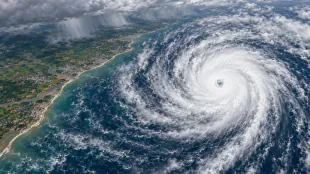 Bay cyclone forecast to strike Andhra-Yanam coast at very severe strength
 UDST opens Fall 2027 admissions to students in Qatar and abroad
 Kuwait legal department reviews new commercial concealment law
 IRDAI gives stakeholders until October 31 to comment on distribution reforms
 Credit-card shortcuts can turn impulse spending into lasting debt
 J&K Bank raises accident cover for government employees to ₹1 crore
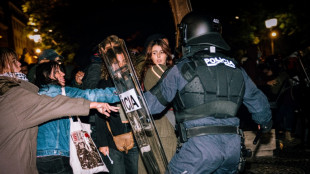
 Far-right leader Le Pen kicks off tilt at French presidency amid nationwide protests
Minimum payments, costly instalments, cash withdrawals and high utilisation can raise borrowing costs and damage a cardholder’s credit profile.
Repeated impulse purchases on a credit card can accumulate into a bill that strains a monthly budget and disrupts longer-term financial goals. The effects often become visible only when the statement arrives, prompting some cardholders to seek short-term ways to avoid paying the full amount.
Paying only the minimum due prevents an immediate default notice and may avoid certain late-payment penalties, but most of the balance remains outstanding and continues to attract interest. Carrying that balance also removes the interest-free grace period on later purchases.
New transactions can then begin accruing interest immediately, commonly at annual rates of 36-42%, compounded monthly, until the account is paid in full. The cost therefore applies not only to the original unpaid amount but also to continuing card use.
Failing to pay even the minimum has more serious consequences. The bank can classify the account as overdue, add late-payment penalties and, after the applicable period, report the delinquency to CIBIL and other credit bureaus. That record can damage the cardholder’s score for an extended time.
Converting a large purchase to equated monthly instalments may make the payment schedule look easier, but it does not remove the expense. The borrower may lose discounts linked to full payment, while 18% goods and services tax is charged on the interest portion of each instalment.
Spreading yesterday’s purchases across future months also reduces the income available for later needs. The product may provide only brief satisfaction while the repayment obligation remains in the household budget.
Timely payment alone does not ensure a strong credit profile. Lenders also examine credit utilisation, the share of the available limit being used. Use above roughly 30% can signal dependence on borrowed money and may lower a CIBIL score even when payments are made on time, affecting future home or vehicle loan applications.
Credit-card cash withdrawals are particularly expensive. Most cards offer no grace period for cash, so interest of 36-42% can start immediately. Some promotional cards advertise an interest-free window, but fixed transaction charges still apply.
A bank may, for example, restrict an individual withdrawal to ₹10,000 and charge about ₹199 plus GST each time. Withdrawing ₹50,000 could therefore require five transactions and generate more than ₹1,000 in processing costs before any interest.
Reward points do not justify unnecessary purchases. Redemption ratios can change, reducing the value of points, while processing fees and GST can consume much of a small redemption.
The financial comparison is therefore between the true cost of the purchase and the realistic value of the reward, not merely the number of points advertised. A purchase made only to earn a benefit can leave the cardholder paying much more in interest, fees or taxes than the redemption is worth.
International purchases also commonly carry a foreign-exchange markup of 1.5-3.5%, plus 18% GST on that fee. The surcharge can apply both while travelling and on certain foreign websites.
Cardholders should also distinguish between a stated credit limit and an affordable spending level. Remaining below the limit does not prevent high utilisation from affecting a credit profile, and the amount must still fit within cash available to settle the full monthly statement.
A credit card can still produce genuine benefits when used with discipline. Products with no joining or annual fee, waived foreign-exchange markups, a useful interest-free period and worthwhile rewards can reduce the cost of ordinary spending. The benefits depend on paying the balance in full and avoiding charges that outweigh the rewards.
X.Wong--CPN