-
 Germany urges EU action against China to defend carmakers
-
Nepal floods among 'most challenging' disasters: WFP
-
 Japan eyes changing prostitution law to punish sex buyers
-
Kids and social media: what would change under new EU law
-
 Modi pitches India as global chipmaking hub
-
King Charles to call on tech giants for 'reassurances' over AI
-
 Ukraine plans record defence spending in 2027
-
STARPRIME Responds to Diverging Gold Market Demand with AM/PM Fixing and XAU24/7
-
 NASA scan discovers new, 'once in a century' Moon crater
-
Where the US-China tariff row stands ahead of White House summit
-
 Most stocks rise as Fed hikes and indicates drive to curb inflation
-
Indonesia cash-for-photos scheme turns animal hunters into protectors
-
 UK-Sudanese author pens book to give children 'African history of Africa'
-
Argentine judge orders suspension of Falklands oil project
-
 US Congress passes sweeping Russia sanctions bill
-
US Fed raises rates to tackle 'too high' inflation, irking Trump
-
 US stocks fall, dollar gains after Fed lifts interest rates
-
Turkey releases 106 protesters, jails more LGBTQ activists
-
 US Fed raises rates to tackle 'too high' inflation in move sure to rile Trump
-
Candidate for UN chief calls for AI regulation akin to nuclear weapons
-
 US Fed raises rates to battle inflation in move likely to rile Trump
-
'We're losing control,' AI pioneer Yoshua Bengio tells AFP
-
 US House faces test on sweeping Russia sanctions bill
-
IR-MED and Dice Technologies Announce collaboration to Evaluate and Advance Pressure-Injury Prevention Platform in Japan
-
 British PM says to make 'difficult decisions' as inflation rises
-
Watts, Pitt, Cruz to light up Spain's top film festival
-
 Global fuel price demos: a round-up
-
Toogood Gold's Table Mountain Sits in the Shadow of a Nevada Gold Rush
-
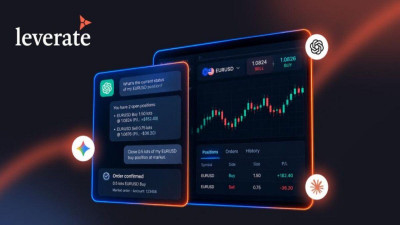 Leverate Launches MCP for Traders to Connect AI Assistants With Trading Platforms
-
MEXC July–August Security Report: 38.66M USDT in Risk Funds Intercepted, Futures Insurance Fund Hits 792M USDT
-
 MEXC Launches $1M "Discover Your Wall Street DNA" Campaign to Help Traders Find Their Market Fit
-
Emporio Armani names Dario Vitale new creative director
-
 Stocks edge higher ahead of US Fed rate call
-
EU to ban social media for under 13s, curb access until 15
-
 BASIS.pro Expands On-Chain Infrastructure with XDC Network Partnership and Zypher DAO as Auto Earn Goes Live
-
Wildfires push endangered Sumatran elephants to brink: Indonesian NGO
-
 Pickle-flavoured tart? AI inspires Japan's convenience stores
-
Bank of Japan set to raise rates under pressure from inflation, US
-
 EU chief hosts Canada's Carney in push to 'deepen' alliance
-
EU chief to unveil social media, gaming curbs for under-15s
-
 Meta chief pushes back on AI slowdown calls
-
'Resident Evil' film brings video game's ethos to the big screen
-
 US Fed to deliver rate decision with markets betting on hike
-
GA-ASI Mojave First UAS To Complete Battlefield Short Field Ops
-
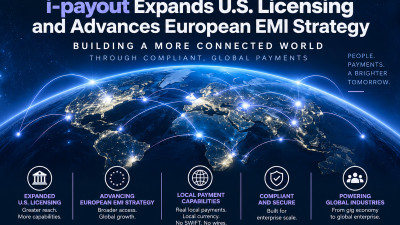 i-payout Expands U.S. Money Transmitter Licensing Footprint and Advances European EMI Strategy
-
Sanders, Bannon warn of AI dangers in rare US left-right alignment
-
 US Senate crypto bill collapses amid partisan deadlock
-
Empty benches as schools reopen in Venezuela's quake-hit Guaira
-
 OpenAI, Anthropic and Google are working to create an AI standards body
-
Tiny English village holds 'independence' vote over asylum seeker housing
Venezuela’s Oil Return
Venezuela is once again being treated as a strategic oil producer rather than as a stranded petrostate. Washington’s effort to mobilise as much as 100 billion dollars for the reconstruction of the country’s energy sector has reopened a market that spent years cut off from capital, technology, equipment and dependable access to international buyers. Rising exports, new operating agreements and the return of international energy executives to Caracas suggest that the revival is no longer merely theoretical.
Yet the description of this initiative as a historic American investment requires precision. The United States government has not transferred a single 100 billion dollar package to Venezuela. What Washington has launched is a politically directed reconstruction strategy designed to attract private capital from American and allied companies. It combines sanctions relief, control over oil revenues, new commercial permissions and pressure for legal reform inside Venezuela.
That distinction matters. Venezuela’s recovery will not be financed by a conventional public aid programme. It will depend primarily on whether companies believe that they can invest billions of dollars, operate fields, export production, receive payment and defend their contractual rights without facing another wave of expropriations or political interference. The opportunity is immense. So are the risks.
From isolated producer to strategic supplier
The decisive break came in January 2026, when the removal of Nicolás Maduro by United States forces overturned the political and commercial structure surrounding Venezuela’s oil industry. The interim administration led by Delcy Rodríguez subsequently began working with Washington on a rapid reopening of the energy sector. Oil revenues generated under the new arrangement are being placed under a system of American oversight. Washington argues that this is necessary to prevent the money from being seized, diverted or used by hostile foreign networks. The mechanism is also intended to preserve funds for Venezuela’s economic stabilisation and reconstruction.
For the United States, the policy serves several objectives simultaneously. It offers American refiners renewed access to a nearby source of heavy crude, reduces the influence of China, Russia and Iran in one of the world’s most resource-rich countries, and creates the prospect of a more commercially aligned energy industry in the Western Hemisphere. For Venezuela, it offers something the country has lacked for years: access to finance, equipment, diluents, drilling services, technical expertise, shipping capacity and solvent customers. The scale of the resource explains the renewed attention. Venezuela holds approximately 303 billion barrels of proven crude oil reserves, the largest officially recorded volume in the world. Most of these reserves lie in the Orinoco Belt and consist of extra-heavy crude. This oil is abundant, but it is neither simple nor cheap to produce.
Extra-heavy crude must often be blended with lighter hydrocarbons before it can move efficiently through pipelines. It requires specialist production techniques, functioning upgraders, reliable electricity and refineries capable of processing high-sulphur feedstock. Venezuela possesses the oil beneath the ground, but much of the industrial system required to turn that oil into reliable revenue has deteriorated.
Iran changed the economic calculation
The renewed interest in Venezuelan oil cannot be separated from the disruption of energy flows from the Middle East. The conflict involving Iran and the severe restrictions affecting traffic through the Strait of Hormuz changed the commercial value of every accessible barrel outside the region. Venezuela cannot replace the enormous quantities normally transported through the Persian Gulf. Its present production remains far too small, and its infrastructure cannot support a sudden multi-million-barrel expansion. Nevertheless, Venezuelan crude has become strategically important because it can provide incremental supply at a time when physical markets are searching for alternatives.
Geography is one of Venezuela’s strongest advantages. Cargoes can reach the United States Gulf Coast far more quickly than shipments from the Middle East. Several large American refineries were originally designed or adapted to process the heavy and sour grades traditionally supplied by Venezuela, Mexico and Canada. This compatibility gives Venezuelan oil a natural market. American refiners do not need Venezuela merely because it possesses enormous reserves. They need access to the particular type of crude their processing systems were built to handle.
The Middle Eastern crisis has therefore accelerated a shift that might otherwise have taken much longer. Venezuelan barrels that were previously treated as politically toxic, commercially uncertain or available only through opaque trading structures are now being presented as part of a wider Western energy-security strategy.
A legal opening after decades of state control
Venezuela’s reformed hydrocarbons legislation is central to the investment campaign. The new framework allows private producers greater operational authority, including the ability to manage projects even when they hold a minority interest alongside the state oil company PDVSA.
Companies may also receive greater control over the commercialisation of their production and the collection of sales proceeds. New production-sharing agreements are intended to provide an alternative to the old joint-venture structure, under which PDVSA retained dominant control despite lacking the money and technical capacity to maintain many projects. The United States has reinforced these reforms through a series of general licences. These authorisations permit specified oil and gas operations, the purchase and marketing of Venezuelan crude, the provision of equipment and technical services, and the sale of American diluents needed to transport extra-heavy oil.
Other permissions allow negotiations and contingent investment contracts for new projects. Contracts involving Venezuelan public entities must contain stronger legal protections, with specified forms of dispute resolution in recognised international jurisdictions. These provisions are designed to answer one of the most important questions confronting investors: what happens when a commercial dispute becomes political? The memory of past nationalisations remains powerful. Foreign companies lost major projects during the period of aggressive state takeovers under Hugo Chávez. Some firms still hold unpaid claims and arbitration awards. Others are owed billions of dollars for previous operations, services or supplies.
No oil company can ignore that history. New legislation may improve the contractual framework, but laws passed during a political transition are valuable only when they are applied consistently and survive future changes of government.
The first barrels are already moving
Despite these uncertainties, Venezuela’s oil recovery has produced visible results. Exports of crude oil and fuel have risen above 1.2 million barrels per day, compared with an average of approximately 847,000 barrels per day in 2025. Around half of current export volumes have been directed towards the United States, while additional cargoes have travelled to Europe and India.
The increase is significant because it demonstrates that existing wells, storage systems and export terminals can deliver more oil when sanctions, shipping and payment restrictions are relaxed. It does not yet prove that Venezuela can sustain a long-term production renaissance, but it has moved the country beyond the stage of political promises. Chevron holds the strongest initial position among American companies. Its Venezuelan joint ventures are producing approximately 280,000 barrels per day, and the company sees a path towards increasing that figure by as much as 50 per cent by the end of 2028, subject to acceptable commercial terms. The company has also strengthened its position in the Orinoco Belt through agreements that concentrate its activities on heavy-oil projects. Existing infrastructure gives Chevron an advantage over companies that would have to rebuild local teams, reopen offices, assess damaged assets and negotiate entirely new contracts.
European energy groups are also moving. Eni is seeking to transform the Junín 5 project into a major production asset. The field currently produces only about 12,000 barrels per day, but the company believes that output could eventually reach a plateau of 200,000 barrels per day once investment resumes. Repsol has pursued additional fields and expanded its negotiations, while Shell has participated in new oil and gas arrangements. Trading companies have established or enlarged teams in Caracas, and international refiners are competing more directly for Venezuelan cargoes.
Interest is no longer confined to the United States. Refiners in Asia are examining Venezuelan crude as part of a broader effort to diversify away from disrupted Middle Eastern supply routes.
A 100 billion dollar ambition is not yet 100 billion dollars of committed capital
The central weakness in Washington’s reconstruction drive is the gap between announced ambition and binding investment decisions. The target of 100 billion dollars describes the scale of capital believed necessary to revive Venezuela’s wider energy system. It does not represent money that has already been committed. Companies have signed memoranda, preliminary agreements and contract-migration documents, but many projects remain delayed by incomplete regulations, technical annexes, tax questions, debt disputes and uncertainty over operational control.
Venezuela established a deadline for converting existing ventures to the new legal framework, yet numerous agreements were still unfinished when that deadline passed. Some companies prefer production-sharing contracts because they provide greater flexibility. Others fear that unresolved projects could eventually be reassigned to competing investors. This is the less dramatic but more consequential phase of the recovery. Political declarations can reopen a country in a matter of weeks. Engineering surveys, financing structures, procurement chains, environmental assessments and legally enforceable contracts take much longer.
The international oil industry is also more financially disciplined than it was during previous commodity booms. Major companies will not commit capital solely because reserves are large or political leaders promise favourable treatment. Projects must compete against opportunities in Guyana, Brazil, the United States, Canada, Argentina and other regions offering more predictable operating conditions. Venezuela must therefore prove that its oil is not merely abundant, but commercially investable.
The infrastructure crisis beneath the export recovery
The greatest physical obstacle is the condition of the country’s infrastructure. Years of deferred maintenance have damaged pipelines, production facilities, storage tanks, refineries, ports, roads and power systems. The Paraguana Refining Centre once represented Venezuela’s industrial strength. Its installed capacity approaches 955,000 barrels per day, but the complex operates at only a fraction of that level. Corrosion, equipment failures, missing components and inadequate maintenance have left major units idle or unreliable.
Restoring Venezuela’s refining system to dependable operation could require at least 20 billion dollars. Rehabilitating the electricity grid may require another 15 billion dollars over several years. The power problem is especially serious because oil production cannot be separated from electricity. Pumps, compressors, water-injection systems, upgrading plants, port facilities and refineries all depend on a stable grid. Repeated blackouts can halt production, damage equipment and delay exports. Private producers may build independent power facilities for individual projects, but this would not solve the wider national crisis. A collection of profitable oil enclaves operating behind their own generators would increase exports without necessarily restoring electricity for Venezuelan homes, hospitals and businesses.
Ports and transport systems create additional bottlenecks. Companies have reported unreliable water supplies, inadequate heavy transport, poor refrigeration and unstable electricity at commercial facilities. These conditions increase operating costs and complicate every stage of project development.
The danger of an export boom without domestic recovery
Venezuela’s rising crude exports contrast sharply with the condition of its domestic fuel system. The country can possess the world’s largest oil reserves and still struggle to supply petrol and diesel reliably to its own population. Domestic refineries have little commercial incentive to improve while fuel is sold at prices that do not cover operating and maintenance costs. Raising prices would improve refinery economics, but it would also impose another burden on a population already affected by poverty, inflation and deteriorating public services.
Foreign investors are likely to prioritise upstream production because crude can be exported and sold for internationally recognised prices. Rebuilding refineries for a heavily subsidised domestic market is less attractive.
This creates a difficult political question. If new investment produces more export revenue but leaves households facing blackouts, fuel shortages and inadequate services, the revival will quickly lose public legitimacy. The success of the reconstruction programme must therefore be measured by more than export volumes. It must also be judged by whether revenue reaches the wider economy, restores infrastructure and improves living conditions.
Debt, arbitration and the price of credibility
Venezuela’s financial crisis extends far beyond the oil sector. Public debt has been estimated at around 180 per cent of gross domestic product even before the full value of international judgments and arbitration claims is added. Much of this debt is in default. The country owes money to bondholders, suppliers, service companies and former investors. A durable recovery will eventually require a broad debt restructuring, a credible fiscal framework and the restoration of relations with international financial institutions. The renewed engagement with the International Monetary Fund is therefore important. Venezuela has regained access to approximately 4.9 billion dollars in reserve assets held through the Fund, while technical discussions are beginning on statistics, institutional capacity and possible future financial support.
No amount of oil investment can substitute for functioning economic institutions. Reliable production data, transparent public accounts, an independent central bank and enforceable commercial rules are essential if Venezuela is to move from emergency financing to normal investment.
The human dimension is equally important. Around eight million Venezuelans have left the country since the economic crisis began. The economy has contracted dramatically, inflation remains severe and public services have deteriorated. An oil recovery that enriches project operators and political intermediaries without creating jobs, stabilising the currency and rebuilding institutions would repeat the central failure of Venezuela’s previous oil booms.
Washington’s geopolitical wager
The American strategy is also an attempt to redraw Venezuela’s international relationships. Sanctions permissions have been structured to favour American and allied companies while limiting participation by entities connected to China, Russia and Iran. For Washington, this is energy policy, commercial policy and geopolitical containment combined. Venezuela’s oil industry had become deeply connected to countries willing to provide equipment, credit or trading channels outside the Western financial system. The new arrangement seeks to redirect those flows towards American-controlled legal, financial and commercial networks.
The Iran conflict has made this strategy more urgent. By promoting Venezuelan production, Washington gains a nearby source of heavy crude while reducing the strategic importance of supply routes vulnerable to disruption in the Middle East.
There is, however, an unavoidable sovereignty debate. American oversight of oil revenues may reduce the risk of immediate diversion, but it also gives Washington considerable influence over Venezuela’s principal source of national income. For the arrangement to remain legitimate, the rules governing revenue, expenditure and investment will need to be transparent. Venezuelans must be able to see how much oil is sold, what prices are received, where the proceeds are held and how the money is used. Without that transparency, a system presented as protection could be interpreted as external control.
Venezuela is back, but the revival has only begun
Venezuela has returned to the global oil map because the combination of geopolitical disruption, American policy and legal reform has made its crude commercially relevant again. Exports are rising, international companies are negotiating new terms and existing projects are preparing for expansion.
The historic element is not a sudden discovery of oil. Venezuela’s reserves have been known for generations. Nor is it the immediate arrival of 100 billion dollars in committed investment. The historic change is the construction of an entirely new political and financial framework around the country’s energy sector. Washington is attempting to convert Venezuela from an isolated and sanctions-dependent producer into a Western-aligned supplier supported by private capital.
Whether that project succeeds will depend on matters that cannot be resolved by executive orders alone. Venezuela needs legal certainty, functioning infrastructure, credible institutions, stable taxation, reliable electricity, transparent revenue management and political legitimacy.
The country can increase production relatively quickly by repairing existing wells and equipment. Returning to the output levels of its former oil era will require many years, enormous capital and a degree of institutional stability that Venezuela has not demonstrated for decades. Venezuela is therefore back on the oil map, but it is not yet restored as an oil power. The next phase will determine whether the present opening becomes a durable national recovery or merely another temporary extraction boom.
Trump announces Homan as new 'border czar'
New York’s lost Luster
Watch Live: Trump or Harris? America votes!
Georgia: Ruling party celebrates election victory
Asylum seekers: Return centres – a Solution?
Climate change: A farm in Rotterdam
EU: Overcoming barriers to equality
Germany and its outdated pension system
How important is sustainable development?
Berlin: EU-Summit of western Balkan heads of state
Putin's War Will Go Bankrupt if the Oil Prices Drop