-
 Micron's Taiwan workers say 68 months' bonus not enough
-
'Another arrow to the quiver': World Bank posts record private capital mobilization
-
 Canada's Carney pushes 'new alliance' with EU despite Trump threats
-
Ireland to boycott Eurovision 2027 over Gaza
-
 Beyond Investment Returns: Families Are Measuring Wealth by Freedom, Continuity, and Legacy, According to Nour Private Wealth
-
India's Tata Sons reappoints N. Chandrasekaran as chairman
-
 King Charles disputes claims in book by Princess Diana's brother
-
Germany urges EU action against China to defend carmakers
-
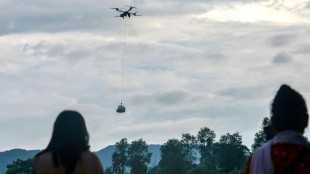 Nepal floods among 'most challenging' disasters: WFP
-
Japan eyes changing prostitution law to punish sex buyers
-
 Kids and social media: what would change under new EU law
-
Modi pitches India as global chipmaking hub
-
 King Charles to call on tech giants for 'reassurances' over AI
-
Ukraine plans record defence spending in 2027
-
 STARPRIME Responds to Diverging Gold Market Demand with AM/PM Fixing and XAU24/7
-
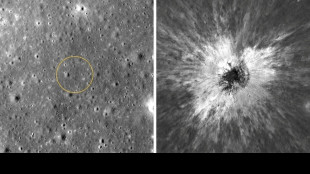
NASA scan discovers new, 'once in a century' Moon crater
-
 Where the US-China tariff row stands ahead of White House summit
-
Most stocks rise as Fed hikes and indicates drive to curb inflation
-
 Indonesia cash-for-photos scheme turns animal hunters into protectors
-
UK-Sudanese author pens book to give children 'African history of Africa'
-
 Bayer to Present How it Rebuilt Global Planning with OMP at Gartner Supply Chain Planning Summit 2026
-
Argentine judge orders suspension of Falklands oil project
-
 US Congress passes sweeping Russia sanctions bill
-
US Fed raises rates to tackle 'too high' inflation, irking Trump
-
 US stocks fall, dollar gains after Fed lifts interest rates
-
Turkey releases 106 protesters, jails more LGBTQ activists
-
 US Fed raises rates to tackle 'too high' inflation in move sure to rile Trump
-
Candidate for UN chief calls for AI regulation akin to nuclear weapons
-
 US Fed raises rates to battle inflation in move likely to rile Trump
-
'We're losing control,' AI pioneer Yoshua Bengio tells AFP
-
 US House faces test on sweeping Russia sanctions bill
-
IR-MED and Dice Technologies Announce collaboration to Evaluate and Advance Pressure-Injury Prevention Platform in Japan
-
 British PM says to make 'difficult decisions' as inflation rises
-
Watts, Pitt, Cruz to light up Spain's top film festival
-
 Global fuel price demos: a round-up
-
Toogood Gold's Table Mountain Sits in the Shadow of a Nevada Gold Rush
-
 Leverate Launches MCP for Traders to Connect AI Assistants With Trading Platforms
-
MEXC July–August Security Report: 38.66M USDT in Risk Funds Intercepted, Futures Insurance Fund Hits 792M USDT
-
 MEXC Launches $1M "Discover Your Wall Street DNA" Campaign to Help Traders Find Their Market Fit
-
Emporio Armani names Dario Vitale new creative director
-
 Stocks edge higher ahead of US Fed rate call
-
EU to ban social media for under 13s, curb access until 15
-
 BASIS.pro Expands On-Chain Infrastructure with XDC Network Partnership and Zypher DAO as Auto Earn Goes Live
-
Wildfires push endangered Sumatran elephants to brink: Indonesian NGO
-
 Pickle-flavoured tart? AI inspires Japan's convenience stores
-
Bank of Japan set to raise rates under pressure from inflation, US
-
 EU chief hosts Canada's Carney in push to 'deepen' alliance
-
EU chief to unveil social media, gaming curbs for under-15s
-
 Meta chief pushes back on AI slowdown calls
-
'Resident Evil' film brings video game's ethos to the big screen
Pension crisis engulfs France
In autumn 2025 the long‑running battle over France’s retirement system morphed from a fiscal headache into an existential crisis. After years of protests and political upheavals, the government admitted that its flagship 2023 pension reform had failed to plug the funding gap. Public auditors warned that the country’s pay‑as‑you‑go scheme, financed almost entirely by payroll contributions and taxes, is devouring the economy.
A February 2025 report from the Cour des Comptes, the national audit office, found that the pension system spends almost 14 % of gross domestic product on benefits—four percentage points more than Germany. Those contributions produced an average monthly pension of €1 626 and gave retirees a living standard similar to that of working people. French pensioners not only enjoy one of Europe’s highest replacement rates but also have one of the lowest poverty rates (3.6 %). The generosity comes at a price: the same audit calculated that the deficit across the various pension schemes will widen from €6.6 billion in 2025 to €15 billion by 2035 and €30 billion by 2045, adding roughly €470 billion to public debt. Raising the retirement age to 65 would help, but even that would yield only an extra €17.7 billion a year.
The French model dates from the post‑war social contract, when four or five workers supported each pensioner. The demographic ratio has now fallen below two, and the number of pensioners is projected to rise from 17 million today to 23 million by 2050. Two‑thirds of the resources allocated to pensions already come from social security contributions, supplemented by a growing share of taxes. Employers’ labour costs are inflated because 28 % of payroll goes to pensioners, making French industry less competitive. Pensions absorb about a quarter of government spending, more than the state spends on education, defence, justice and infrastructure combined.
Reform fatigue and political paralysis
Successive administrations have tried to curb the rising bill but have been derailed by street protests and parliamentary rebellions. In April 2025 the Cour des Comptes bluntly warned that keeping the system unchanged is “impossible”; it argued that people must work longer and that pensions should be indexed more closely to wages rather than inflation. The 2023 reform, which is supposed to raise the statutory retirement age gradually from 62 to 64 by 2030, barely maintained balance until 2030 and did nothing to close the long‑term gap. When the government sought to postpone a routine pension hike to mid‑2025 to save €4 billion, opposition parties branded the proposal a theft from the elderly. Marine Le Pen’s far‑right National Rally and other groups blocked the measure, and even ministers within the governing coalition disavowed it. A 5.3 % pension increase granted in January 2024 to protect retirees from inflation cost €15 billion a year, wiping out most of the savings from pushing back the retirement age.
Popular resistance is fuelled by the fact that French workers already retire earlier than almost anyone else in the European Union. Although the legal age is now 62, the effective retirement age is only 60.7 years. OECD data show that French men spend an average of 23.3 years in retirement, far longer than in Germany (18.8 years). The low retirement age and high replacement rate mean pensions replace a larger share of pre‑retirement income than in most countries. With a median voter now in their mid‑40s, governments have little incentive to antagonise older voters, leading to what economists call a “demographic capture” of democracy. Reforms are generally adopted only when markets force governments’ hands—Greece, Portugal and Sweden passed painful changes under the threat of financial collapse.
Economic consequences
France’s public finances are straining under the weight of pension obligations. The country’s debt reached 114 % of GDP in June 2025, and interest payments are projected to exceed €100 billion by 2029, becoming the single largest budget item. In September 2025 Fitch downgraded France’s credit rating to A+, citing the lack of a clear plan to stabilise the debt. Political instability has made matters worse: Prime Minister François Bayrou was ousted in a no‑confidence vote in September after proposing a €44 billion deficit‑cutting plan. His successor, Sebastien Lecornu, immediately suspended the 2023 pension reform until after the 2027 presidential election, effectively throwing fiscal prudence out of the window to preserve his government. Investors now demand a higher risk premium on French bonds than on those of Spain or Greece.
The escalating pension bill is crowding out spending on education, infrastructure and innovation, sapping France’s potential for future growth. Economists warn that the longer reform is delayed, the more abrupt and painful it will need to be. Raising the retirement age beyond 65, modifying the generous indexation to inflation, broadening the tax base and encouraging more people to work past 55 are options that could restore sustainability. Without such measures, the pension system will continue to devour the nation’s finances, leaving younger generations to shoulder an ever‑heavier burden.
Conclusion
France’s pension crisis is not unique in Europe, but its scale and political toxicity are. The system reflects a post‑war social contract that promised long, comfortable retirements financed by ever‑fewer workers. That contract is now broken. Auditors, economists and even some politicians agree that the status quo is unsustainable and that tough choices lie ahead. Yet the clash between an ageing electorate intent on defending its privileges and a political class unwilling to tell voters hard truths has created an impasse. Unless France confronts its demographic realities and curbs the generosity of its pension system, the country will remain caught in a fiscal doom loop where pensions devour its economy and there is nothing to be done—until the markets force change.
AI sparks Wall Street panic
EU India deal gains unveiled
Japan’s right‑turn triumph
U.S. Jobs stall, gdp slows
Strike fears rise over Iran
No red lines: Israel vs Iran
Is that Israel's final blow?
Iran and the holy War risk
Cuban regime nears collapse
Iran-War and dangerous Lines
BlackRock fund freeze panic