Coin Press - Why copper mines fell short

NYSE - LSE
CMSD -0.54% 18.65 $
NGG 0.13% 79.82 $
BTI -1.11% 56.84 $
AZN -0.61% 174.35 $
CMSC -1.35% 18.9 $
BCE 2.42% 21.86 $
GSK -0.13% 47.76 $
RYCEF -7.13% 16.4 $
RIO -2.71% 72.73 $
RBGPF -0.4% 75 $
BCC -2.17% 63.01 $
RELX -0.75% 38.54 $
BP -1.08% 42.75 $
VOD -1.15% 14.02 $
JRI -1.71% 10.53 $

Why copper mines fell short


Chile’s copper mines and Freeport’s operations in Indonesia produced roughly 530,000 fewer tonnes of copper in the first nine months of 2026 than they had a year earlier. At Grasberg, fewer tonnes of rock are reaching the mills, and each contains less metal. In Congo, the owners of another giant mine are turning to shallow deposits while crews work to reclaim flooded ground.

It took rescue crews 27 days to reach the last five of the seven men who died at Grasberg in Indonesia. On September 8, 2025, about 800,000 tonnes of wet material rushed from the former open pit into the workings below. It reached several levels, including the one where the men were found. More than a year later, the route the material took through the mountain still shapes how much copper the mine can produce.

The same figure, 800,000 tonnes, has been put forward as the combined copper loss at six large mines. Verifying that estimate would require a common period and a production baseline for each mine. Some losses can be measured against the previous year’s output. Others are tonnes an expansion was supposed to deliver. At one Chilean mine, the choice of comparison changes even the direction of the result.

The long way back at Grasberg
Two production blocks at Grasberg began reopening at the end of March 2026. By the third quarter, the district’s mills were treating about 141,000 tonnes of ore a day, roughly two-thirds of capacity. Freeport expects to bring another block back into service in mid-2027 and to approach full capacity across the district by the end of that year. Its timetable allows months for upgrading the equipment that moves broken rock through the mine.

The ore reaching the mills has also been leaner. In the first nine months of 2025, each tonne contained an average of 11.4 kilograms of copper before processing. A year later it contained 8.9 kilograms. The mills recovered a slightly larger share of the copper in the rock, but they had less rock to process and less metal in each load. The Indonesian business produced 549 million pounds of recoverable copper through September, down from 966 million. In metric tonnes, the difference was about 189,000.

In Congo, a different route to the ore
Before seismic activity and flooding hit the Kakula mine in May 2025, the Kamoa-Kakula complex in the Democratic Republic of the Congo expected to produce between 520,000 and 580,000 tonnes of copper in concentrate that year. It finished with about 389,000 tonnes. Measured against the midpoint of the original plan, around 161,000 tonnes of expected output failed to materialise in 2025 alone.

At Kakula, crews are building a new pumping system to regain access to parts of the mine. In the meantime, Ivanhoe Mines and its partners plan to remove the overlying rock from shallow deposits at Kamoa in early 2027, with the first ore due in the third quarter. That gives the processing plants another place to draw feed from while crews work at Kakula. In November, Ivanhoe put expected 2026 production at about 290,000 tonnes of copper in saleable products and cut its 2027 forecast to between 300,000 and 350,000 tonnes.

What the Chilean figures conceal
Chile produced 3.63 million tonnes of fine copper in the first nine months of 2026, down from 3.97 million a year earlier. El Teniente was still operating under restrictions after the July 2025 collapse that killed six workers. Its first-half production fell 27 per cent year on year. At Collahuasi, severe weather and the need to process lower-grade ore from stockpiles weighed on third-quarter production.

At Quebrada Blanca, August snow and high winds interrupted power to the plant that separates copper minerals from waste rock. Wet ground also made it harder to reach the richer ore. The mine produced 47,200 tonnes of copper in the third quarter, down from 55,800 in the preceding three months. Yet it was well ahead of the 39,600 tonnes it had produced a year earlier, when work to raise the tailings dam had cost it 20 operating days. At Los Pelambres, drawing down stocks built up in the previous quarter helped lift reported output. Both mines show how much can turn on when the copper is counted.

Why smelters feel the squeeze
For a smelter, the shortage shows up in the price it can charge to turn concentrate into metal. Antofagasta agreed to supply a Chinese smelter in 2026 at a treatment charge of zero. Competition for feed had eroded a traditional source of smelter income. At the same time, recycling offers another route to refined copper, and production is increasing at mines including Oyu Tolgoi in Mongolia. In October, global refined copper production was still projected to exceed use by about 104,000 tonnes in 2026.

That projected annual surplus offers little comfort to a buyer who needs metal in a particular place this week. On November 16, the expiring Shanghai copper contract jumped more than nine per cent as sellers scrambled to cover deliveries. Four days later, three-month copper in London traded as low as $12,202 a tonne, down from its September record of $14,875. A manufacturer in China could watch the international price fall and still have to pay a premium to get copper through the factory gate on time.


Featured


Long live Ukraine - Хай живе Україна - Да здравствует Украина

Es lebe die Ukraine - Да здравствует Украина - Long live Ukraine - Хай живе Україна - Nech žije Ukrajina - Länge leve Ukraina - תחי אוקראינה - Lang leve Oekraïne - Да живее Украйна - Elagu Ukraina - Kauan eläköön Ukraina - Vive l'Ukraine - Ζήτω η Ουκρανία - 乌克兰万岁 - Viva Ucrania - Ať žije Ukrajina - Çok yaşa Ukrayna - Viva a Ucrânia - Trăiască Ucraina - ウクライナ万歳 - Tegyvuoja Ukraina - Lai dzīvo Ukraina - Viva l'Ucraina - Hidup Ukraina - تحيا أوكرانيا - Vivat Ucraina - ขอให้ยูเครนจงเจริญ - Ucraina muôn năm - ژوندی دی وی اوکراین - Yashasin Ukraina - Озак яшә Украина - Živjela Ukrajina - 우크라이나 만세 - Mabuhay ang Ukraine - Lenge leve Ukraina - Nyob ntev Ukraine - Да живее Украина - გაუმარჯოს უკრაინას - Hidup Ukraine - Vivu Ukrainio - Længe leve Ukraine - Živjela Ukrajina - Жыве Украіна - Yaşasın Ukrayna - Lengi lifi Úkraína - Lank lewe die Oekraïne

Stargate project, Trump and the AI war...

In a dramatic return to the global political stage, former President Donald J. Trump, as the current 47th President of the United States of America, has unveiled his latest initiative, the so-called ‘Stargate Project,’ in a bid to cement the United States’ dominance in artificial intelligence and outpace China’s meteoric rise in the field. The newly announced programme, cloaked in patriotic rhetoric and ambitious targets, is already stirring intense debate over the future of technological competition between the world’s two largest economies.According to preliminary statements from Trump’s team, the Stargate Project will consolidate the efforts of leading American tech conglomerates, defence contractors, and research universities under a centralised framework. The former president, who has long championed American exceptionalism, claims this approach will provide the United States with a decisive advantage, enabling rapid breakthroughs in cutting-edge AI applications ranging from military strategy to commercial innovation.“America must remain the global leader in technology—no ifs, no buts,” Trump declared at a recent press conference. “China has been trying to surpass us in AI, but with this new project, we will make sure the future remains ours.”Details regarding funding and governance remain scarce, but early indications suggest the initiative will rely heavily on public-private partnerships, tax incentives for research and development, and collaboration with high-profile venture capital firms. Skeptics, however, warn that the endeavour could fan the flames of an increasingly militarised AI race, raising ethical concerns about surveillance, automation of warfare, and data privacy. Critics also question whether the initiative can deliver on its lofty promises, especially in the face of existing economic and geopolitical pressures.Yet for its supporters, the Stargate Project serves as a rallying cry for renewed American leadership and an antidote to worries over China’s technological ascendancy. Proponents argue that accelerating AI research is paramount if the United States wishes to preserve not just military supremacy, but also the economic and cultural influence that has typified its global role for decades.Whether this bold project will succeed—or if it will devolve into a symbolic gesture—remains to be seen. What is certain, however, is that the Stargate Project has already reignited debate about how best to safeguard America’s strategic future and maintain the balance of power in the fast-evolving arena of artificial intelligence.

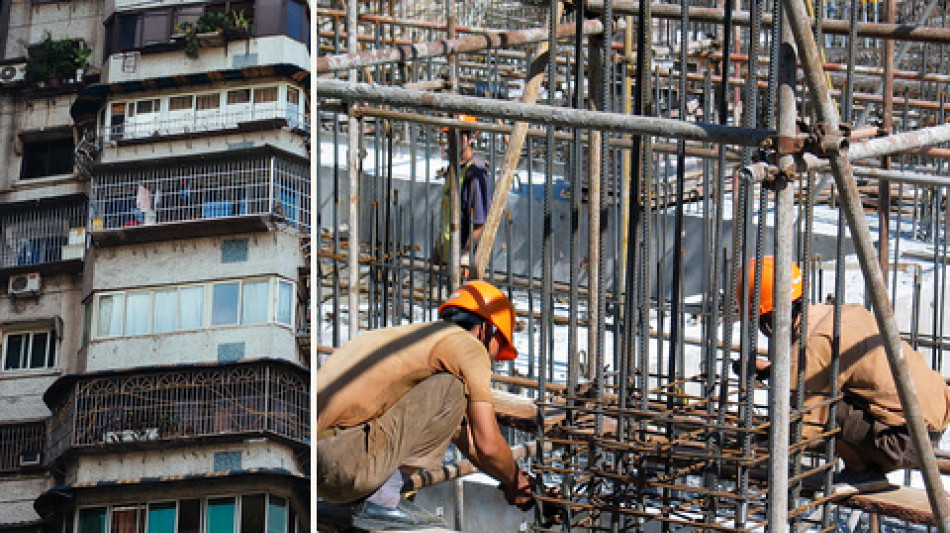
China’s local debt comes home

In Zunyi, a city in southwestern China, the banks agreed to wait a decade for the first yuan of principal. At the end of 2022, the city-owned Zunyi Road and Bridge Construction Group reached an agreement with its lenders on 15.6 billion yuan in loans. It would pay interest for ten years and repay the principal over the following ten. On that schedule, the banks will still be collecting on loans from China’s building boom in the early 2040s.Nearly four years later, the land market that once sustained local borrowing is still shrinking. Across China, local governments raised 1.85 trillion yuan from granting rights to use state-owned land in the first ten months of 2026, down 25.8 percent from a year earlier. For a household with a mortgage, the same property slump can mean a home worth less than its owners paid for it. For the city where they live, it means fewer developers willing to bid for the next plot. Both still owe money borrowed in better years.Land acquired this outsized role partly because of a tax reform in 1994. Beijing took a larger share of revenue while provinces, cities and counties remained responsible for much of the cost of schools, health care and infrastructure. Central transfers covered part of the gap. A fast-growing city had another option. It could grant a developer long-term rights to a site and collect much of the value of those rights up front.Local officials could also set up a company to borrow from banks or sell bonds. These companies, known as local government financing vehicles, helped pay for roads, bridges and industrial parks. A new road could attract factories and make the surrounding plots more valuable. The city could then collect more at its next land auction. Lenders had reason to expect municipal backing even when the company alone had signed the loan agreement.The weak point was the distance between what a project was worth to a city and what it earned for its owner. A free road could cut the cost of getting goods to market without generating a yuan in tolls. As long as developers bid more for nearby land, the city had a way to cover the difference. Once the housing market turned in 2021, some borrowers needed another loan to service the last one. That dependence on fresh money is what invites the comparison with a pyramid scheme. It also explains how a city can own valuable infrastructure and still struggle to pay a bill.Beijing’s response has changed who signs for the debt:In November 2024, lawmakers approved an extra six trillion yuan in local borrowing authority over three years to refinance eligible hidden debt. A further 800 billion yuan a year was earmarked from existing special bond quotas for five years, bringing the package to ten trillion yuan. By November 11, 2026, local governments had issued about 99 percent of the six-trillion-yuan tranche, shifting obligations once carried off the books onto public balance sheets. A province can borrow more cheaply and for longer than a troubled municipal company. The interest saving is real. The principal still falls due.Beijing has also tightened scrutiny of new projects in heavily indebted regions. That curbs the ability of one city to borrow for an industrial park simply because its neighbor is building one. It leaves local officials with less discretion over worthwhile projects as well. In October 2026, Beijing allocated 300 billion yuan of unused borrowing capacity to help counties and urban districts meet day-to-day expenses. Keeping existing services running now competes for borrowing capacity once associated with building new ones.Families can feel the squeeze even while the city pays its bondholders on time:Local financing companies have fallen behind on bills to suppliers. A contractor waiting for a municipal client to settle an invoice still has to find the cash for wages and materials. In effect, the business is lending the city money every week the bill goes unpaid.For homeowners, the loss can be more lasting. A fall in an apartment’s resale value reduces the equity available to owners who need to move, while the bank still has a claim on the outstanding mortgage. Cheaper homes help prospective buyers, but a worker whose next paycheck depends on construction has a reason to postpone buying. Investment in residential buildings fell 21.4 percent in the first ten months of 2026. Families also have medical bills and retirement to plan for. As the cushion provided by housing equity shrinks, keeping more cash in the bank makes sense. Beijing is counting on those same households to spend more.In Shangqiu, in Henan province, residents have already seen how narrowly a public service can survive a cash shortage. In February 2023, the city’s bus operator announced that it would suspend services, citing pandemic losses and a subsidy shortfall. It said it could no longer pay staff or charge its electric buses. The city intervened within hours and the buses kept running. The banks in Zunyi could wait a decade for a principal payment. Shangqiu’s passengers needed a bus the next morning.