-
 Germany urges EU action against China to defend carmakers
-
Nepal floods among 'most challenging' disasters: WFP
-
 Japan eyes changing prostitution law to punish sex buyers
-
Kids and social media: what would change under new EU law
-
 Modi pitches India as global chipmaking hub
-
King Charles to call on tech giants for 'reassurances' over AI
-
 Ukraine plans record defence spending in 2027
-
STARPRIME Responds to Diverging Gold Market Demand with AM/PM Fixing and XAU24/7
-
 NASA scan discovers new, 'once in a century' Moon crater
-
Where the US-China tariff row stands ahead of White House summit
-
 Most stocks rise as Fed hikes and indicates drive to curb inflation
-
Indonesia cash-for-photos scheme turns animal hunters into protectors
-
 UK-Sudanese author pens book to give children 'African history of Africa'
-
Argentine judge orders suspension of Falklands oil project
-
 US Congress passes sweeping Russia sanctions bill
-
US Fed raises rates to tackle 'too high' inflation, irking Trump
-
 US stocks fall, dollar gains after Fed lifts interest rates
-
Turkey releases 106 protesters, jails more LGBTQ activists
-
 US Fed raises rates to tackle 'too high' inflation in move sure to rile Trump
-
Candidate for UN chief calls for AI regulation akin to nuclear weapons
-
 US Fed raises rates to battle inflation in move likely to rile Trump
-
'We're losing control,' AI pioneer Yoshua Bengio tells AFP
-
 US House faces test on sweeping Russia sanctions bill
-
IR-MED and Dice Technologies Announce collaboration to Evaluate and Advance Pressure-Injury Prevention Platform in Japan
-
 British PM says to make 'difficult decisions' as inflation rises
-
Watts, Pitt, Cruz to light up Spain's top film festival
-
 Global fuel price demos: a round-up
-
Toogood Gold's Table Mountain Sits in the Shadow of a Nevada Gold Rush
-
 Leverate Launches MCP for Traders to Connect AI Assistants With Trading Platforms
-
MEXC July–August Security Report: 38.66M USDT in Risk Funds Intercepted, Futures Insurance Fund Hits 792M USDT
-
 MEXC Launches $1M "Discover Your Wall Street DNA" Campaign to Help Traders Find Their Market Fit
-
Emporio Armani names Dario Vitale new creative director
-
 Stocks edge higher ahead of US Fed rate call
-
EU to ban social media for under 13s, curb access until 15
-
 BASIS.pro Expands On-Chain Infrastructure with XDC Network Partnership and Zypher DAO as Auto Earn Goes Live
-
Wildfires push endangered Sumatran elephants to brink: Indonesian NGO
-
 Pickle-flavoured tart? AI inspires Japan's convenience stores
-
Bank of Japan set to raise rates under pressure from inflation, US
-
 EU chief hosts Canada's Carney in push to 'deepen' alliance
-
EU chief to unveil social media, gaming curbs for under-15s
-
 Meta chief pushes back on AI slowdown calls
-
'Resident Evil' film brings video game's ethos to the big screen
-
 US Fed to deliver rate decision with markets betting on hike
-
GA-ASI Mojave First UAS To Complete Battlefield Short Field Ops
-
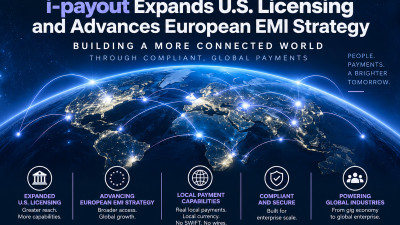 i-payout Expands U.S. Money Transmitter Licensing Footprint and Advances European EMI Strategy
-
Sanders, Bannon warn of AI dangers in rare US left-right alignment
-
 US Senate crypto bill collapses amid partisan deadlock
-
Empty benches as schools reopen in Venezuela's quake-hit Guaira
-
 OpenAI, Anthropic and Google are working to create an AI standards body
-
Tiny English village holds 'independence' vote over asylum seeker housing
Israel: Economy on the edge
After two years of fighting in Gaza and growing international isolation, Israel’s economy is facing unprecedented strains. Once a regional growth engine, the country now grapples with ballooning war costs, surging consumer prices, labour shortages, crumbling public finances and a declining credit standing. The signs of distress are evident across households, businesses and government accounts.
War‑Related Damage and Fiscal Strain
The war in Gaza, which began after the October 7 2023 attacks, has inflicted both human and economic devastation. Gaza’s authorities estimate that more than 67 000 Palestinians have been killed and Israel reports that Hamas killed 1 200 people in the initial attack. Economic activity in Gaza and the West Bank has collapsed. The conflict has cost the Israeli economy about US$43 billion since October 2023 and has slowed GDP growth from high single‑digit rates to 0.9 % in 2024. Defence spending is expected to almost double compared with 2022, pushing the debt‑to‑GDP ratio from 61 % in 2023 to roughly 70 % in 2024 and swelling the budget deficit to 8.5 % of GDP.
Israel has financed wartime expenditure through borrowing. The state raised US$8 billion on international markets in March 2024 and US$5 billion in February 2025, relying partly on US military aid. However, analysts warn that war‑related labour shortages and the ongoing mobilisation of reservists are stalling growth: the central bank trimmed its 2025 growth estimate to 2.5 %, down from 3.3 %, and sees the economy expanding only if hostilities end. A former deputy governor estimated that failure to achieve a lasting ceasefire could push debt above 90 % of GDP by 2030, triggering credit downgrades.
Cost‑of‑Living Crisis and Tax Hikes
Consumers are feeling the pinch. Israel ranks among the developed world’s most expensive countries; its price levels are the fourth highest in the OECD. The Organisation for Economic Co‑operation and Development (OECD) attributes high prices to a mix of geographical constraints, steep tariffs on food imports, strict product‑market regulations and limited competition. Administrative red tape and complex planning rules restrict housing supply, while a vibrant high‑tech sector coexists with low‑productivity industries, creating large wage disparities. In 2025 the state comptroller warned that the cost of living was skyrocketing: prices for basic goods were 51 % higher than those in the European Union and 37 % above the OECD average, with three corporations controlling over 85 % of many food categories. These monopolistic structures enable retailers to raise prices during times of shortage.
At the start of 2025, Israelis faced further blows. The value‑added tax was raised from 17 % to 18 %, increasing the cost of nearly all goods. National Insurance contributions were increased by ₪1 000–2 000 per household, income tax brackets were frozen so that salaries do not keep pace with inflation and the surtax on high earners rose from 3 % to 5 %. Municipal property taxes can rise 5.2 %, with higher levies on newer buildings, while electricity prices climb 3.5 % and water charges 2 %. These measures are intended to narrow the fiscal gap caused by wartime expenditure but further squeeze households’ disposable income and risk fuelling social unrest.
High Cost of Living and Structural Problems
Israel’s cost‑of‑living problem is not new. Protests against soaring housing and food prices date back more than a decade, from the 2011 tent protests to the 2014 “Milky” boycott. Analysis by the OECD highlights deep structural causes. Israel’s distance from major trading partners and tense regional relations limit trade opportunities, while difficult border procedures, complex regulatory standards and tariffs on agricultural imports raise import costs. Limited competition and strict product‑market regulation slow productivity growth and prevent savings from being passed on to consumers. Housing is particularly unaffordable: administrative red tape restricts supply and planning obstacles make urban development sluggish.
The OECD therefore recommends sweeping reforms: remove trade barriers and bureaucratic hurdles to strengthen competition, establish a “one‑stop shop” for business licensing and adopt a “silence is consent” principle for issuing permits, simplify import licensing and lower tariffs on vegetables, fruit and dairy. Easing planning regulations, accelerating urban renewal and investing in public transport would expand housing supply and reduce costs. Without such measures, high prices will continue to erode purchasing power.
Labour Shortages, Inequality and the High‑Tech Exodus
Labour markets have been disrupted on multiple fronts. The war caused schools and services to close and led to the suspension of Palestinian work permits, halving the share of non‑Israeli labour in total employment and cutting investment by 26 % in late 2023. Agriculture and construction struggled as Palestinian and foreign workers were barred, while the call‑up of reservists removed tens of thousands of Israelis from civilian jobs. The central bank warns that the economy will not recover fully until these supply constraints ease.
Meanwhile, inequality has deepened. Before the war, Israel’s GDP per capita was 14 times higher than that of Gaza and the West Bank. In Gaza, GDP has shrunk by 86 % and multi‑dimensional poverty now afflicts 98 % of residents. Within Israel, labour‑force participation is low among ultra‑Orthodox men and Arab women, hindering growth. The OECD urges the government to end subsidies for yeshiva students, condition childcare support on fathers’ employment and equalise funding for Arab schools.
Israel’s high‑tech industry, which accounts for about a fifth of GDP, more than half of exports and roughly a quarter of tax revenue, is facing its own crisis. In the nine months after the October 2023 attacks, 8 300 high‑tech employees left the country for year‑long relocations. High‑tech employment declined by 5 000 jobs in 2024, the first contraction in at least a decade. The Israel Innovation Authority warns that the exodus reflects uncertainty about the war’s duration, a lack of funding and the call‑up of reservists. It calls for investment in education and skills, tax incentives for returning professionals and policies to stabilise the business environment. Without such measures, a core driver of growth and tax revenue may erode.
Housing Market Slump
The real estate sector, once a key wealth store for Israeli households, has also stalled. In June 2025, housing sales fell to the lowest level in more than two decades; only 5 844 units were sold, a 29 % drop from a year earlier, and sales of new‑build homes collapsed by 46 %. These figures mark the lowest June sales since the early 2000s. The Ministry of Finance attributed the slump to war‑related uncertainty and tighter financing rules. The national housing price index declined by 1.3 % over four months, with Tel Aviv seeing a 4.2 % drop. Some Israelis are turning to real estate abroad, including Georgia, to protect wealth. Analysts warn that the market’s collapse reflects a broader decline in consumer confidence and investment.
International Isolation and Credit Downgrades
Israel’s global standing has deteriorated. The war’s humanitarian toll has hardened attitudes in the European Union, Israel’s largest trading partner. Several EU states have frozen arms exports, and some have moved to ban imports from Israeli settlements. In September 2025 the European Commission proposed suspending trade benefits covering 37 % of Israeli exports, amounting to roughly €42.6 billion in annual trade. The plan, which would end preferential tariffs and impose sanctions on Israeli ministers, marks Brussels’ strongest action yet against Israel. Such measures threaten to curb exports, investment and access to technology.
Credit rating agencies have responded by lowering Israel’s sovereign rating and warning of further downgrades. In February 2024 Moody’s cut the rating two notches from A2 to Baa1 and maintained a negative outlook. In early 2025, Fitch affirmed an “A” rating but retained a negative outlook, citing rising public debt, domestic political strains and the uncertain trajectory of the Gaza war. Fitch noted that renewed hostilities could last months, reducing reserves mobilised but still straining the economy. All three major agencies cut Israel’s score in 2024 due to ballooning defence and civilian costs, signalling that borrowing costs could rise and limiting fiscal flexibility.
The Bank of Israel, which has kept its benchmark interest rate at 4.5 % for 14 consecutive meetings, warns that international isolation will harm trade and foreign investment. Governor Amir Yaron cautions that prolonged conflict could lower growth, widen the budget deficit and keep inflation high. Despite pressure from industry to cut rates, the central bank stresses that supply constraints, war‑driven budgets and a strong shekel justify caution. Inflation peaked at 3.8 % in January 2025 but moderated to 2.5 % in September, within the target range.
Prospects and Necessary Reforms
Looking ahead, forecasts hinge on peace. The OECD projects that if fighting eases, Israel’s economy could grow 3.4 % in 2025 and 5.5 % in 2026. A ceasefire allowing reservists to return to work could lift growth to 3.6 % in 2026, keeping debt below 70 % of GDP. However, the Bank of Israel’s staff anticipates only 2.5 % growth in 2025 and inflation around 3 %, with interest rates declining modestly in 2026. The 2025 budget aims to narrow the deficit to 4.3 %, but economists expect it could still reach 5 %.
To avert lasting damage, structural reforms are essential. The OECD urges the government to relax product‑market regulations, reduce trade barriers and red tape, improve infrastructure and invest in education and labour‑market participation for ultra‑Orthodox and Arab citizens. It calls for ending subsidies that discourage work, tying childcare support to parental employment, and equalising funding for Arab schools. Investment in artificial intelligence and advanced skills is needed to sustain the high‑tech sector, which the innovation authority says must broaden its talent pool. The cost‑of‑living crisis requires the dismantling of monopolies, lowering tariffs on food imports and streamlining planning regulations.
Conclusion
Israel’s economy is in serious trouble. Years of war have drained public finances, weakened growth and raised debt to unprecedented levels. Households face higher taxes, surging utility bills and some of the world’s highest consumer prices. Labour shortages, inequality and the exodus of high‑tech talent threaten long‑term competitiveness, while credit downgrades and EU trade sanctions signal growing international isolation. Without a durable peace and a bold reform agenda—spanning trade liberalisation, regulatory simplification, education and competition policy—the country risks prolonged stagnation and social unrest. The coming months will determine whether Israel can arrest its economic decline or whether the cracks widen into a full‑blown crisis.
Argentina's radical Shift
Al-Qaida’s growing ambitions
Saudi shift shakes Israel
BRICS-Dollar challenge
Trap laid, Ukraine walked in
AI bust: Layoffs & Rent surge
COSTCO profits from Fees
Trump's threats to Colombia
United Kingdom vs Immigration
UK politics: Outlook for 2026
Trump preps Allies for Ven Op