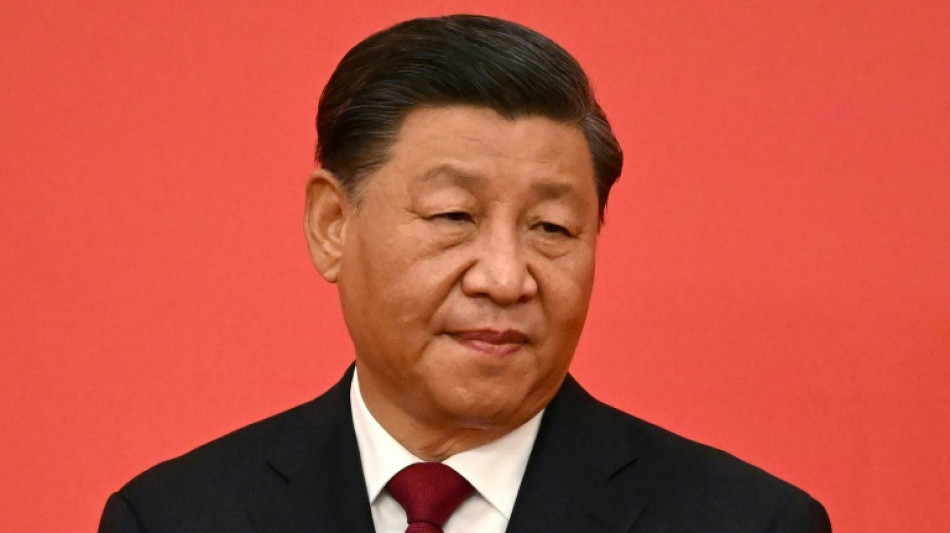
China economy grows, but Xi's new power spooks investors / Photo: Noel CELIS - AFP
 French businessman takes over 2030 Winter Olympics amid leadership turmoil
 Stock markets diverge on corporate earnings, tech jitters
 TotalEnergies profit hits record on high oil prices
 Afghanistan opium poppy cultivation surges despite Taliban govt ban: UN
 Microsoft beats expectations fueled by Azure cloud business
 Shares in Google owner Alphabet sink on profit miss, ad slowdown
 Pioneering US labor leader Dolores Huerta dies at 96
 US Fed holds interest rates steady despite surging inflation
 US labor leader Dolores Huerta dead: family
 French firm Safran helps build aircraft wings of the future in UK factory
 World Bank warns of worsening food insecurity as commodity prices soar
China's economy grew at a faster pace than forecast in the third quarter, official data showed Monday, but investors reacted with alarm to President Xi Jinping's sweeping new powers over the ruling Communist Party.
Xi as expected secured a third term as leader at a party Congress over the weekend, but surprised observers with his complete stacking of other leadership positions with proteges and allies.
After delaying the release of economic data last week so it would not conflict with the Congress, the government announced Monday the economy grew 3.9 percent year-on-year in the third quarter.
China had been expected to announce some of its weakest quarterly growth figures since 2020, with the world's second-biggest economy hobbled by Covid restrictions and a real estate crisis.
But investors instead focused on the political developments, which raised fears Xi and his allies would continue with gruelling Covid lockdowns and other policies that have punished the economy.
The currency of the world's second-largest economy slumped and the country's stocks nosedived in Hong Kong to their lowest level since the global financial crisis.
On Monday the onshore yuan dipped as much as 0.4 percent to 7.2552 per dollar -- its weakest since January 2008 -- and the Hang Seng China Enterprises Index, a gauge of Chinese stocks listed in Hong Kong, plunged more than 5 percent.
That put it on track for the worst showing after any Communist Party Congress since the start of the index in 1994.
"The market is concerned that with so many Xi supporters elected, Xi’s unfettered ability to enact policies that are not market friendly is now cemented," said Justin Tang, head of Asian research at United First Partners.
One of the most pressing concerns is Xi's zero-Covid policy, which continues to see tens of millions of people endure rolling lockdowns that also shutter factories.
China is the last of the world's major economies to continue following the strategy.
"There is no clear sign of a significant easing of the zero-Covid strategy," Nomura's Ting Lu said, noting that, if anything, the opposite had happened.
In a speech to close the Congress on Saturday, Xi insisted his zero-Covid policy had been a success.
And he promoted Li Qiang, the architect of a two-month lockdown in Shanghai that crippled the financial hub's economy, to the second most powerful post in the Communist Party.
Tech firms were among the worst hit in Monday's sell-off, having been hammered in recent years by Xi's crackdown on the sector that has scythed firms' profits and wiped billions off their valuations.
E-commerce giants Alibaba and JD.com tanked more than 10 percent each, while Tencent lost more than eight percent.
China is also battling an unprecedented crisis in its real estate sector -- which makes up more than a quarter of the country's GDP when combined with construction.
Following years of explosive growth fuelled by easy access to loans, Xi oversaw a crackdown on excessive debt that began in 2020.
Property sales are now falling across the country, leaving many developers struggling and some owners refusing to pay their mortgages for unfinished homes.
Still, the economic data released on Monday gave some cause for optimism.
The third-quarter growth was higher than the 2.5 percent predicted by a panel of experts surveyed by AFP.
"Many economic indicators have actually recovered reasonably well from the mass lockdowns of March and April," according to analyst Thomas Gatley of Gavekal Dragonomics.
Car sales held strong in September, driven by strong demand for electric clean vehicles.
August exports increased 7.1 percent compared with the previous year, and Beijing has invested in infrastructure to support activity.
In the second quarter of the year, growth had collapsed to 0.4 percent on-year, the worst performance since 2020.
The country posted 4.8 percent growth in the first quarter of 2022.
Many economists continue to think China will struggle to attain its 2022 growth target of around 5.5 percent, and the International Monetary Fund has lowered its GDP growth forecast to 3.2 percent for 2022 and 4.4 percent for next year.
-- Bloomberg News contributed to this story --
D.Goldberg--CPN