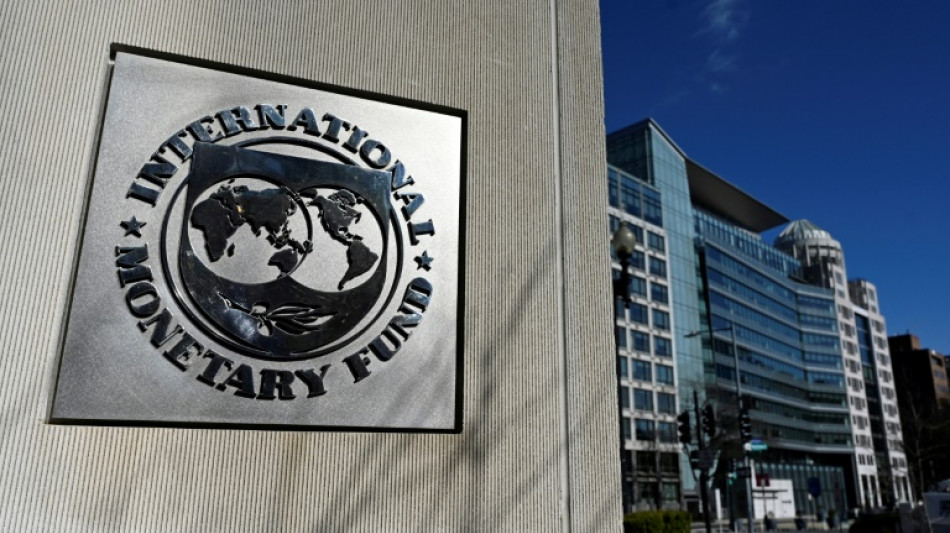
IMF approves revival of massive Pakistan loan program / Photo: OLIVIER DOULIERY - AFP/File
 Samsung logs record quarterly profits despite investor AI jitters
 Shares in Google owner Alphabet plummet on profit miss, ad slowdown
 US Fed holds interest rates steady despite 'too high' inflation
 Airbus aims for record deliveries despite disappointing quarter
 Real Madrid, La Liga apology over Mbappe shows power of Chinese market
 'Cruise for life' strands passengers in Cambodia as operator goes bust
 Canada hikes rates to contain oil price surge caused by Iran war
 Nintendo producer 'all nervous' as Zelda classic remake hits shelves
 Three killed by storm in southern India
 Two hundred 'Cruise for life' passengers stranded in Cambodia
 Billionaire Ambani's Jio jumps 21% in market debut after record India IPO
The IMF board on Monday approved an agreement to revive a massive loan program for Pakistan, as the country grapples with devastating monsoon flooding that has worsened an economic crisis.
The Washington-based crisis lender will release $1.1 billion to the country immediately, and has added an additional $500 million to the total size of the package, bringing it to about $6.5 billion.
In addition, the International Monetary Fund agreed to the government's request to extend the package through June 2023.
The original $6 billion bailout package was signed by former prime minister Imran Khan in 2019, but repeatedly stalled when his government reneged on agreed reforms on subsidies and failed to significantly improve tax collection.
The aid comes as "Pakistan's economy has been buffeted by adverse external conditions, due to spillovers from the war in Ukraine, and domestic challenges," said IMF Deputy Managing Director Antoinette Sayeh in a statement.
"Steadfast implementation of corrective policies and reforms remain essential to regain macroeconomic stability, address imbalances and lay the foundation for inclusive and sustainable growth," she said.
The government reached an agreement with IMF staff last month to restart the suspended aid package.
The new agreement follows months of deeply unpopular belt-tightening by the government of Shehbaz Sharif, who took power in April and has effectively eliminated fuel subsidies and introduced new measures to broaden the tax base.
Finance Minister Miftah Ismail, announcing the approval on Twitter, applauded Sharif "for taking so many tough decisions and saving Pakistan from default."
The latest disbursement brings the total received under the IMF Extended Fund Facility to about $4 billion.
- Desperate for aid -
Pakistan is desperate for international support for its economy, which suffers from poor revenue collection and dwindling foreign reserves to pay its crippling debt.
The new government has slashed a raft of subsidies to meet the demands of global financial institutions, but risks the wrath of an electorate already struggling under double-digit inflation.
Sharif's new coalition government has said it will make the tough decisions needed to turn the economy around.
Successive administrations have blamed their predecessors for the country's economic woes, but analysts say the malaise stems from decades of poor management and a failure to tackle endemic corruption and widespread tax avoidance.
In a bid to secure the IMF loan, Sharif has imposed three fuel price hikes -- cumulatively totalling 50 percent -- and raised the cost of electricity to effectively end the subsidies introduced by Khan.
Ismail told the national assembly last month that the steps were "essential" to preserve the country from default.
"We knew it would damage our political reputation, but still we did it," he said.
The latest budget has earmarked 3.95 trillion rupees ($18.8 billion) just to service the country's whopping debt of $128 billion.
Sayeh welcomed the government's intention to achieve a small budget surplus in 2023.
"Containing current spending and mobilizing tax revenues are critical to create space for much-needed social protection and strengthen public debt sustainability," she said.
She also called recent interest rate increases a "necessary step" to rein in inflation.
Under the deal agreed with the IMF, policy priorities included steadfast implementation of the budget to reduce the need to borrow.
Pakistan also agreed to continue power sector reforms, tighten monetary policy to tackle inflation, strengthen governance, combat corruption and improve the social security net.
Y.Ibrahim--CPN