China calls for urgent boost to virus-hit economy / Photo: Hector RETAMAL - AFP
 Nintendo producer 'all nervous' as Zelda classic remake hits shelves
 Three killed by storm in southern India
 Two hundred 'Cruise for life' passengers stranded in Cambodia
 Billionaire Ambani's Jio jumps 21% in market debut after record India IPO
 Sri Lanka's Tamil farmers fight to reclaim land after civil war
 'They don't care about us': Trump food aid cuts leave Americans struggling and angry
 Palestinian activist Khalil returns to Columbia after US detention
 Youths testify about 'despair' in unprecedented Canadian climate trial
 Storied Paris department store seeks bankruptcy protection
 Boeing shares tumble after it releases cautious growth forecast
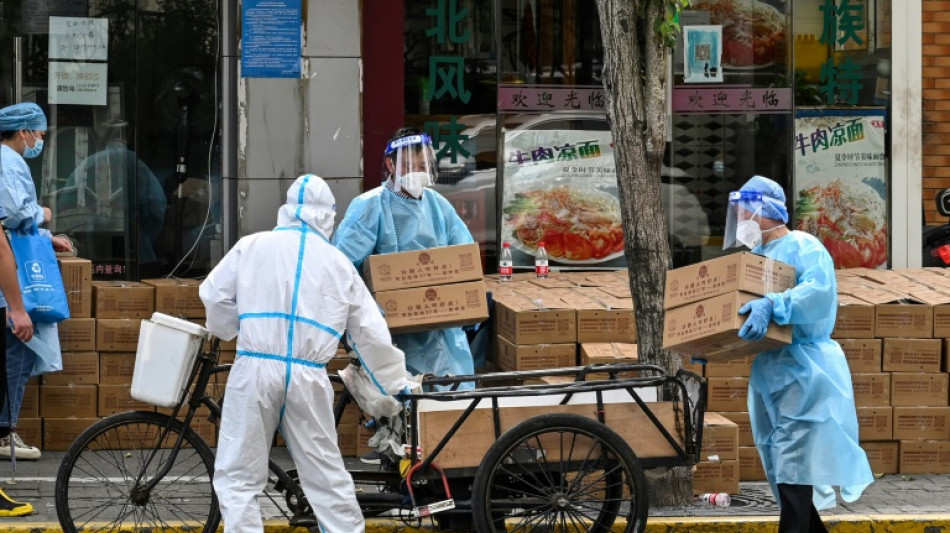
China's premier called for greater "urgency" in rolling out measures to support the virus-battered economy, state media reported Wednesday, days after data highlighted the stark impact of Covid-19 restrictions.
China -- the last major global economy sticking to a rigid zero-Covid policy -- is battling an economic slump due to prolonged virus lockdowns that have constricted supply chains, quelled demand and stalled manufacturing.
"All localities and departments should step up their sense of urgency, and new measures that can be used should be used," Li Keqiang said at a symposium on Wednesday, according to state broadcaster CCTV.
He added that efforts to support the economy should bring it "back to normal quickly" after admitting that indicators have "weakened significantly" since March, with a particular dip in April.
On Monday, data showed retail sales and factory output last month had slumped the most since the start of the pandemic, while unemployment edged back toward its February 2020 peak.
Beijing's unrelenting approach to Covid-19 outbreaks has snarled supply chains and locked down tens of millions of people, hitting major financial, industrial and tourist hubs.
The country's borders also remain closed to most foreign travellers and a slew of international sports events have been scrapped over pandemic concerns.
China has targeted full-year growth of around 5.5 percent, but data published in April showed that first-quarter growth slowed to 4.8 percent after the world's second-biggest economy lost steam in the latter half of last year.
And the economic targets have a political dimension for Chinese leader Xi Jinping, who is eyeing another term in power.
Xi has pinned his legacy to China's strong economic growth and winning the "battle" against Covid.
But the current outbreak is the country's worst since the virus emerged in Wuhan in late 2019, and the economy is beginning to weaken.
- Tech support -
Li also called Wednesday for backing Chinese tech companies' bids to list domestically and abroad, a day after Communist Party leaders doubled down on support for the tech sector in a rare meeting with executives.
China's economic slowdown appears to have motivated a softer approach toward the vast, money-spinning tech sector, after an 18-month clampdown driven by fears massive internet companies control too much data and expanded too quickly.
Vice Premier Liu He and other Communist leaders addressed executives, including Robin Li of Baidu -- universally used for its search engine and mapping service -- and Zhou Hongyi of internet security firm Qihoo 360, state media reported late Tuesday.
Liu offered support for "the sustainable and healthy development of the platform economy and the private economy," CCTV said.
During the tech crackdown, overseas IPOs from Alibaba's Ant Group and Didi Chuxing -- China's Uber -- were spiked, while millions of dollars of fines over anti-trust and data breaches were ladled out to tech giants.
Chinese tech shares surged late April after officials pledged support for internet firms at a Politburo meeting.
Tech giants including Alibaba, Tencent and Baidu were marginally lower Wednesday morning, with e-commerce behemoth JD slumping over 4 percent after it recorded a 3 billion yuan ($444 million) loss in first-quarter earnings.
On Wednesday, Tencent reported record-low quarterly revenue growth at nearly zero, reaching the slowest pace since the company went public in 2004.
Y.Ponomarenko--CPN