Tokyo spearheads equities selloff on US recession fears / Photo: Richard A. Brooks - AFP
 Vessel operator seeks witnesses after Vancouver grounding
 Shrini Srivastava joins crew of Varanasi-Delhi Vande Bharat Sleeper service
 Nearly Half of Australian Workers Overqualified, Survey Finds
 RBI eases export-declaration compliance for individual service exporters
 Reliance shares remain in focus after near-12% surge
 Coal India prepares possible $1 billion Mahanadi Coalfields listing
 Capital-markets shares rally as Motilal Oswal and Angel One lead gains
 Reliance rally puts historical one-year return pattern in focus
 Saudi Aramco quarterly profit climbs 34.6% amid elevated oil prices
 Australia raises benchmark rate to highest level in 18 years
 Asian stocks retreat as AI worries outweigh steep oil-price drop
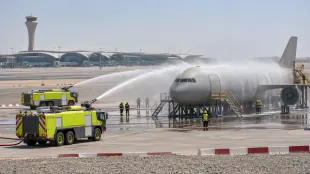 Hamad International Airport stages emergency drills during WATAN 2026
Tokyo tanked Friday as it led losses across Asia due to a stronger yen and expectations for more Japanese rate hikes, with equities also slammed after weak data sparked fears of a US recession and a plunge on Wall Street.
The anguish spilled over into Europe with Frankfurt, London and Paris sliding before key US non-farm payrolls data, which will give a clearer snapshot of the world's biggest economy.
"The market is currently scared that the US economy is slowing faster than had been expected and the tone of the US payrolls report will be key in either soothing or accentuating these fears," Rabobank analyst Jane Foley told AFP.
The optimism that greeted Federal Reserve boss Jerome Powell's indication on Wednesday that borrowing costs could be cut in September has given way to trepidation that the US slowdown might be more pronounced than previously thought.
The Fed has for months been looking for confirmation that inflation is well on the way down and the labour market is softening, while at the same time trying to avoid a sharp plunge in business activity. It has largely been confident in achieving a "soft landing".
But news Thursday that the US factory sector shrunk faster than forecast in July -- and for the fourth consecutive month -- raised eyebrows. That came as another report showed the private sector created far fewer jobs than expected in July -- and many fewer than in June.
The private sector added 122,000 jobs in July, down from June's revised 155,000 figure, while unemployment claims also spiked more than anticipated.
That dealt a blow to investors, who are also dealing with a disappointing earnings season from Big Tech, a key driver of the global rally that has helped push many markets to multiple record highs this year.
US chip titan Intel became the latest bearer of bad news, warning it would slash more than 15 percent of its workforce -- about 18,000 jobs -- as it streamlines operations. The firm reported a loss of $1.6 billion in the recently ended quarter.
All three main indexes tumbled in New York on Thursday, with the Nasdaq more than two percent off.
Asia fared just as poorly on Friday with tech taking the brunt of the selling.
The Nikkei 225 tanked 5.8 percent -- its biggest drop since the start of the pandemic four years ago -- owing to a stronger yen, which hits Japan's key export sector.
Hong Kong and Sydney were off more than two percent, Seoul gave up more than three percent and Taipei shed more than four percent, with losses also in Shanghai, Mumbai, Bangkok, Singapore and Jakarta.
Wednesday's decision by the Bank of Japan to hike interest rates for the second time in 17 years -- and talk of another to come -- strengthened the yen to its best level since March.
The pound extended losses against the greenback, a day after the Bank of England cut its main interest rate for the first time since the Covid pandemic broke out in 2020.
- Key figures around 1050 GMT -
London - FTSE 100: DOWN 0.6 percent at 8,232.83 points
Paris - CAC 40: DOWN 1.0 percent at 7,300.50
Frankfurt - DAX: DOWN 1.6 percent at 17,793.52
Euro STOXX 50: DOWN 1.8 percent at 4,680.21
Tokyo - Nikkei 225: DOWN 5.8 percent at 35,909.70 (close)
Hong Kong - Hang Seng Index: DOWN 2.1 percent at 16,945.51 (close)
Shanghai - Composite: DOWN 0.9 percent at 2,905.34 (close)
New York - Dow: DOWN 1.2 percent at 40,347.97 (close)
Dollar/yen: DOWN at 148.80 yen from 149.66 yen on Thursday
Euro/dollar: UP at $1.0819 from $1.0750
Pound/dollar: UP at $1.2736 from $1.2735
Euro/pound: UP at 84.94 pence from 84.71 pence
West Texas Intermediate: UP 0.3 percent at $76.56 per barrel
Brent North Sea Crude: UP 0.3 percent at $79.75 per barrel
O.Hansen--CPN