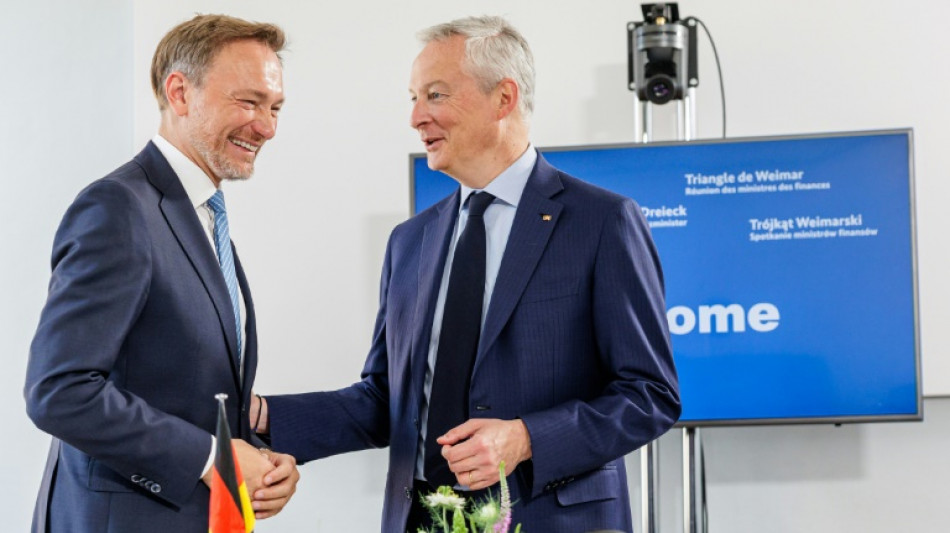
EU strikes budget reform deal after two-year wrangle / Photo: JENS SCHLUETER - AFP
 Vessel operator seeks witnesses after Vancouver grounding
 Shrini Srivastava joins crew of Varanasi-Delhi Vande Bharat Sleeper service
 Nearly Half of Australian Workers Overqualified, Survey Finds
 RBI eases export-declaration compliance for individual service exporters
 Reliance shares remain in focus after near-12% surge
 Coal India prepares possible $1 billion Mahanadi Coalfields listing
 Capital-markets shares rally as Motilal Oswal and Angel One lead gains
 Reliance rally puts historical one-year return pattern in focus
 Saudi Aramco quarterly profit climbs 34.6% amid elevated oil prices
 Australia raises benchmark rate to highest level in 18 years
 Asian stocks retreat as AI worries outweigh steep oil-price drop
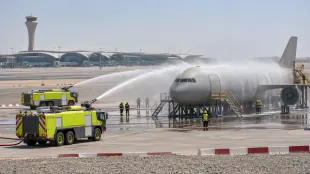 Hamad International Airport stages emergency drills during WATAN 2026
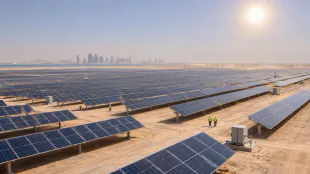 Qatar solar expansion opens scope for technical performance gains
The EU agreed reforms Wednesday that will loosen budget rules with the goal of encouraging investments while keeping debt and spending under control, after France and Germany bridged their differences.
Finance ministers from the 27 members met by video link to hammer out the agreement -- after their French and German colleagues had got together in Paris on Tuesday to clear the way for a compromise.
France's finance minister Bruno Le Maire took to social media to hail the deal. "Historic accord! After two years of intense negotiations we have new European budget rules," he said.
Dutch minister Sigrid Kaag said: "This agreement provides for fiscal rules that encourage reforms, with room for investments and tailored to the specific situation of the member state in question.
"They work counter-cyclically so that potential economic growth is not cut short. In addition, rules must also be better adhered to, which too often has been an issue in the past."
The fiscal straitjacket imposed on EU members -- limiting countries' debt to 60 percent of GDP and public deficits to 3 percent -- was loosened during the Covid pandemic to allow greater state spending.
This was meant to be a temporary reprieve, but launched a two-year debate between countries led by Germany that wanted a return to rigorous controls and others led by France that wanted more flexibility to allow spending to finance, for example, the transition to green energy or arms deliveries to Ukraine.
The compromise deal reconfirms the three percent deficit target. But it softens the rules for how quickly and a severely a country has to cut spending to get back within the parameters.
"It was a hard road. It was a difficult path to tread. And now we have finally reached safe harbour at a historic moment," Spanish finance minister Nadia Calvino, whose country holds the EU presidency, said after the video conference.
"The rules are more realistic. They respond to the post-pandemic reality and they incorporate also the lessons learned from the great financial crisis."
Time had been running out for a deal.
If there was no new plan the original stability pact would have come back into force on January 1.
- Route back to stability -
Failure to agree new rules would have also damaged the EU's credibility in the eyes of the financial markets.
Now that there is political agreement, the EU member states will seek endorsement from the European Parliament to pass binding legislation before elections in June.
The draft text provides for rules more adapted to the particular situation of each country, allowing big spenders a slower route back to frugality.
Brussels is proposing that member states present their own adjustment trajectory over a period of at least four years in order to ensure the sustainability of their debt.
Reform and investment efforts would be rewarded by the possibility of extending this budgetary adjustment period to seven years so that it is less brutal.
The targets would be linked to evolution of expenditure, an indicator considered by some more relevant than deficits, which can fluctuate according to the level of growth.
In order to satisfy Germany, however, countries with excessive deficits will be forced to make a minimum effort to reduce their deficit, which could be 0.5 percentage points per year.
Paris, however, won from Berlin a pause of this effort in 2025 to 2027. Over this period the increase in the cost of debt linked to high interest rates will be taken into account
Berlin also wants a public deficit target of 1.5 percent of GDP be assigned to the most indebted countries, in order to preserve a margin of safety in relation to the three-percent ceiling.
To achieve that, an adjustment of at least 0.4 points of GDP per year will be required, which can be reduced to 0.25 points in the event of reforms and investments.
The debt will have to fall by one percentage point per year on average over four or to seven years.
Compared to the old rules, a French official argued "the deficit target is less restrictive, the pace of reaching it is more progressive and rewards investment".
Y.Jeong--CPN