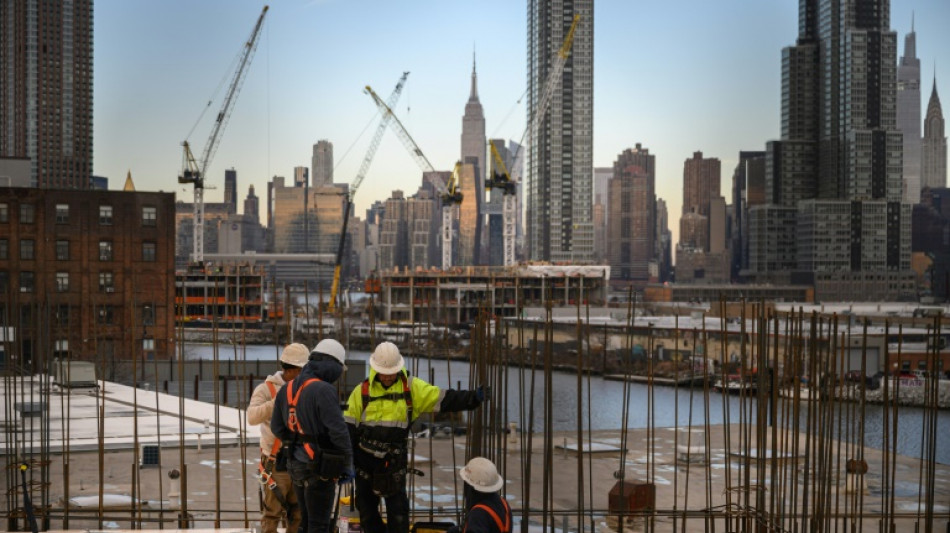
Markets drop as traders nervously await US jobs data / Photo: Ed JONES - AFP/File
 British king reflects on colonial atrocities in Guyana
 Monaco taken off global money-laundering 'grey list'
 Tears, fear, anger: relatives of Spain train crash dead await fate
 Wall Street tech rout deepens on doubts over AI spending
 Relatives' anguish grows as Spain identifies train crash dead
 Markets lashed by tech rout as earnings fan AI fears
 Tech sell-off deepens as earnings fan AI fears
 BP net profit quadruples as Mideast war lifts oil prices
 Drugs giant AstraZeneca reveals higher profits, savings plan
 French economy 'headed for a wall' as GDP shrinks
 South Korea to prosecute students cheating with smart glasses
 Shock, vindication, regret: Scientists react to AI roiling life's work
Asian stocks mostly fell Thursday ahead of key US jobs data at the end of the week, after Federal Reserve boss Jerome Powell warned it could ramp up its pace of interest rate hikes if the economy shows no sign of slowing.
Markets have been falling since the start of February as a string of forecast-beating indicators have shattered hopes the US central bank could pause its tightening campaign soon, and even cut borrowing costs by the year's end.
And on Tuesday, Powell delivered another blow by telling lawmakers that with inflation still stubbornly high and the jobs market tight, officials were prepared to hike by half a percentage point at their next meeting as they struggle to control prices.
That would be twice the last increase, which followed a period of bumper increases last year.
The prospect of rates going ever higher -- with some predicting six percent from the current 4.5-4.75 percent -- has ramped up fears the world's top economy could tip into recession. Analysts pointed out that bond markets suggest a contraction is on the cards.
He reiterated monetary policymakers' determination to quell inflation on Wednesday in a second day of testimony to US lawmakers, though he did say the decision would be driven by data, with a close eye on the labour market.
"If -- and I stress that no decision has been made on this -- but if the totality of the data were to indicate that faster tightening is warranted, we'd be prepared to increase the pace of rate hikes," he said.
"Inflation is coming down but it's very high," he added. "Some part of the high inflation that we are experiencing is very likely related to a very tight labour market."
Meanwhile, the Fed's "beige book" survey of economic conditions said "inflationary pressures remained widespread" and that "labour market conditions remained solid".
- Recession fears hit oil -
Powell's comments "helped briefly pull yields lower and pull the US dollar off its highs for the day, but the reality remains that markets are slowly starting to come to the realisation that rates are likely to remain higher for longer and that the terminal rate is also likely to settle at a much higher level", said CMC Markets' Michael Hewson.
Traders are now awaiting Friday's non-farm payrolls figures for February, with a strong reading likely to put pressure on the Fed to hike by 50 basis points.
In a worrying sign for risk appetite, a report on the private sector showed a bigger-than-expected jump in jobs last month -- double January's number -- while wage growth remained solid.
After a tepid day on Wall Street, Asian markets mostly edged down.
Hong Kong was flat while Shanghai fell with Singapore, Seoul, Wellington, Taipei, Mumbai and Manila. London, Paris and Frankfurt followed suit at the open.
Tokyo, Sydney, Bangkok and Jakarta rose.
Growing concerns about rising rates causing a possible recession were keeping pressure on oil prices, which extended Wednesday's losses.
"Crude prices can't shake off fears that the Fed is going to send the US economy into a bad recession," said OANDA's Edward Moya, adding that data showing a small dip in US stockpiles was unable to shake off the unease.
"The amount of crude demand uncertainty over the short-term is keeping oil prices heavy. WTI crude looks like it will be stuck between the mid-$70s and the low $80s until we have a better idea on what type of recession the Fed will trigger."
- Key figures around 0820 GMT -
Tokyo - Nikkei 225: UP 0.6 percent at 28,623.15 (close)
Hong Kong - Hang Seng Index: DOWN 0.6 percent at 19,925.74 (close)
Shanghai - Composite: DOWN 0.2 percent at 3,276.09 (close)
London - FTSE 100: DOWN 0.3 percent at 7,909.47
Euro/dollar: UP at $1.0554 from $1.0547 on Wednesday
Pound/dollar: UP at $1.1847 from $1.1845
Euro/pound: UP at 89.09 pence from 89.01 pence
Dollar/yen: DOWN at 136.83 yen from 137.43 yen
West Texas Intermediate: DOWN 0.2 percent at $76.51 per barrel
Brent North Sea crude: DOWN 0.2 percent at $82.51 per barrel
New York - Dow: DOWN 0.2 percent at 32,798.40 (close)
Ch.Lefebvre--CPN