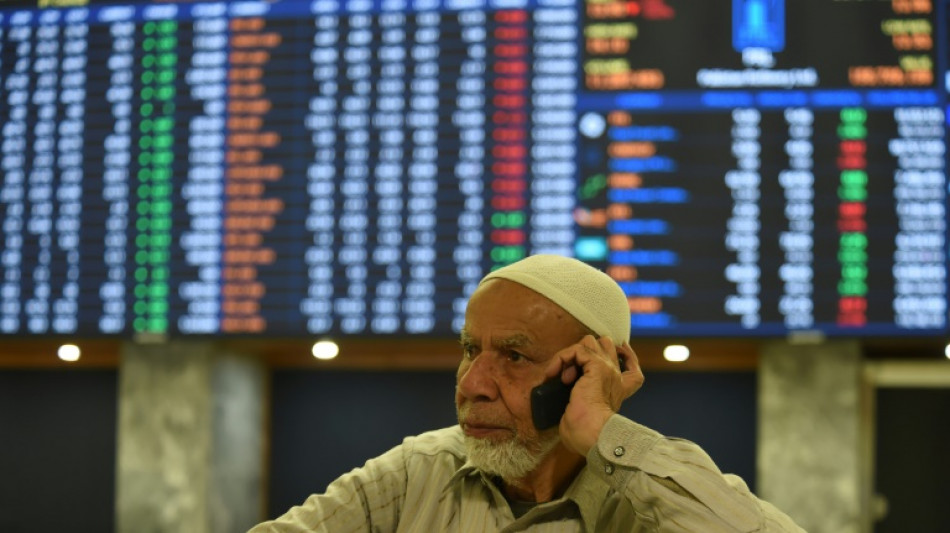
Pakistan's economy in 'collapse' as IMF visits / Photo: Asif HASSAN - AFP
 EU and Canada to 'withstand shocks together' with new alliance

 'Life in the old dog': German economy grows more than expected
 Italy inflation surges to 5.4% as economy stalls
 US oil giants report profit surge again on Iran war
 Carmaker Audi cuts outlook again on China, US woes
 German economy logs 0.2% growth, faster than expected
 China denies spying on Nvidia's Jensen Huang
 BP net profit quadruples on higher oil prices
 Malawi's fuel shortages, record prices deepen economic crisis
 The Duskbloods delayed as Nintendo Switch 2 release moves to 2027
 Tech firms take fresh hit as earnings misses fan AI fears
 Nvidia's web of AI bets: smart strategy or bubble risk?
 DoorDash shares rise as Instacart slips following $17 billion takeover plan
 Amazon cloud business accelerates but shares drop on profit miss
 PI Industries plans Indian launch of Pioxaniliprole insecticide this rabi season
 Asian equities diverge after mixed technology earnings and Fed rate decision
 Kuwait traffic authority cautions against hazard lights while driving in rain
 Utah files criminal charges against prediction market Kalshi
 Kuwait National Guard official visits member injured during training
 CNN Global Perspectives prepares Doha debut with international speaker lineup
 Es’hailSat and Arabsat agree broader satellite and broadcasting cooperation
Pakistan is gripped by a major economic crisis, with the rupee plummeting, inflation soaring and energy in short supply as IMF officials visit to discuss a vital cash injection.
Prime Minister Shehbaz Sharif for months held out against the tax rises and subsidy slashing demanded by the International Monetary Fund, fearful of backlash ahead of elections due in October.
But in recent days, with the prospect of national bankruptcy looming and no friendly countries willing to offer less painful bailouts, Islamabad has started to bow to pressure.
The government loosened controls on the rupee to rein in a rampant black market in US dollars, a step that caused the currency to plunge to a record low. Artificially cheap petrol prices have also been hiked.
"We're at the end of the road. The government has to make the political case to the public for meeting these (IMF) demands," former World Bank economist Abid Hasan told AFP.
"If they don't, the country will certainly default and we'll end up like Sri Lanka, which will be even worse."
Sri Lanka defaulted on its debt last year and endured months of food and fuel shortages that sparked protests, ultimately forcing the country's leader to flee overseas and resign.
In Pakistan, time is of the essence, with Nasir Iqbal from the Pakistan Institute of Development Economics warning the economy had already "virtually collapsed" due to mismanagement and political turmoil.
- Cost-of-living crisis -
The IMF delegation will arrive on Tuesday to a nation in panic, still reeling from unprecedented floods that submerged a third of its territory.
The world's fifth-biggest population has less than $3.7 billion in the state bank -- enough to cover just three weeks of imports.
It is no longer issuing letters of credit, except for essential food and medicines, causing a backlog of thousands of shipping containers at Karachi port stuffed with stock the country can no longer afford.
Industry has been hammered by the imports block and massive rupee devaluation. Public construction projects have halted, textiles factories have partially shut down and domestic investment has slowed.
In downtown Karachi, dozens of day labourers including carpenters and painters wait with their tools on display for work that never comes.
"The number of beggars has increased and the number of labourers has decreased," said 55-year-old mason Zafar Iqbal, who was eating biriyani from a plastic bag donated by a passerby.
"Inflation is so high that one cannot earn enough."
At the petrol pump, a widow with her son said every few hundred rupees (75 cents) of fuel for their motorcycle was precious, with the pair only eating two meals a day.
"The cost is so high that we eat our breakfast late and the second meal at around seven, with nothing in between," said Ulfat, who declined to give her second name.
- Political mayhem -
Pakistan is locked in an endless cycle of servicing external debt.
State Bank governor Jamil Ahmed last month said the country owed $33 billion in loans and other foreign payments before the end of the fiscal year in June.
A diplomatic offensive has seen $4 billion rolled over by lending nations, with $8.3 billion still on the negotiating table.
Meanwhile, Pakistan is battling severe energy shortages -- with capacity drained by poor infrastructure and mismanagement -- compounding the misery of businesses and citizens.
Last week the whole country was plunged into a day-long blackout because of a fault in the national grid that followed a cost-cutting measure.
State petroleum minister Musadik Malik told reporters in Islamabad that imports of Russian oil would start in April, paid for in currencies of "friendly countries" in a mutually beneficial deal.
The tumbling economy mirrors the country's political chaos, with former prime minister Imran Khan heaping pressure on the ruling coalition in his bid for early elections while his popularity remains high.
Khan, who was ousted last year in a no-confidence motion, negotiated a multi-billion-dollar loan package from the IMF in 2019.
But he reneged on promises to cut subsidies and market interventions that had cushioned the cost-of-living crisis, causing the programme to stall.
It is a common pattern in Pakistan, where most people live in rural poverty, with more than two dozen IMF deals brokered and then broken over the decades.
"Even if Pakistan avoids default, the underlying structural factors that triggered the current crisis -- one exacerbated by poor leadership and external global shocks -- will still be in place," tweeted political analyst Michael Kugelman, the director of the South Asia Institute at the Wilson Center in Washington.
"Barring difficult, large-scale reforms, the next crisis could be just around the corner."
L.Peeters--CPN